



Denise is helping her mom, who’s 62, check her IRA. Three funds, set up about ten years ago: 50% U.S. stocks, 10% international, 40% bonds. She hasn’t touched it since.
Why a mix drifts
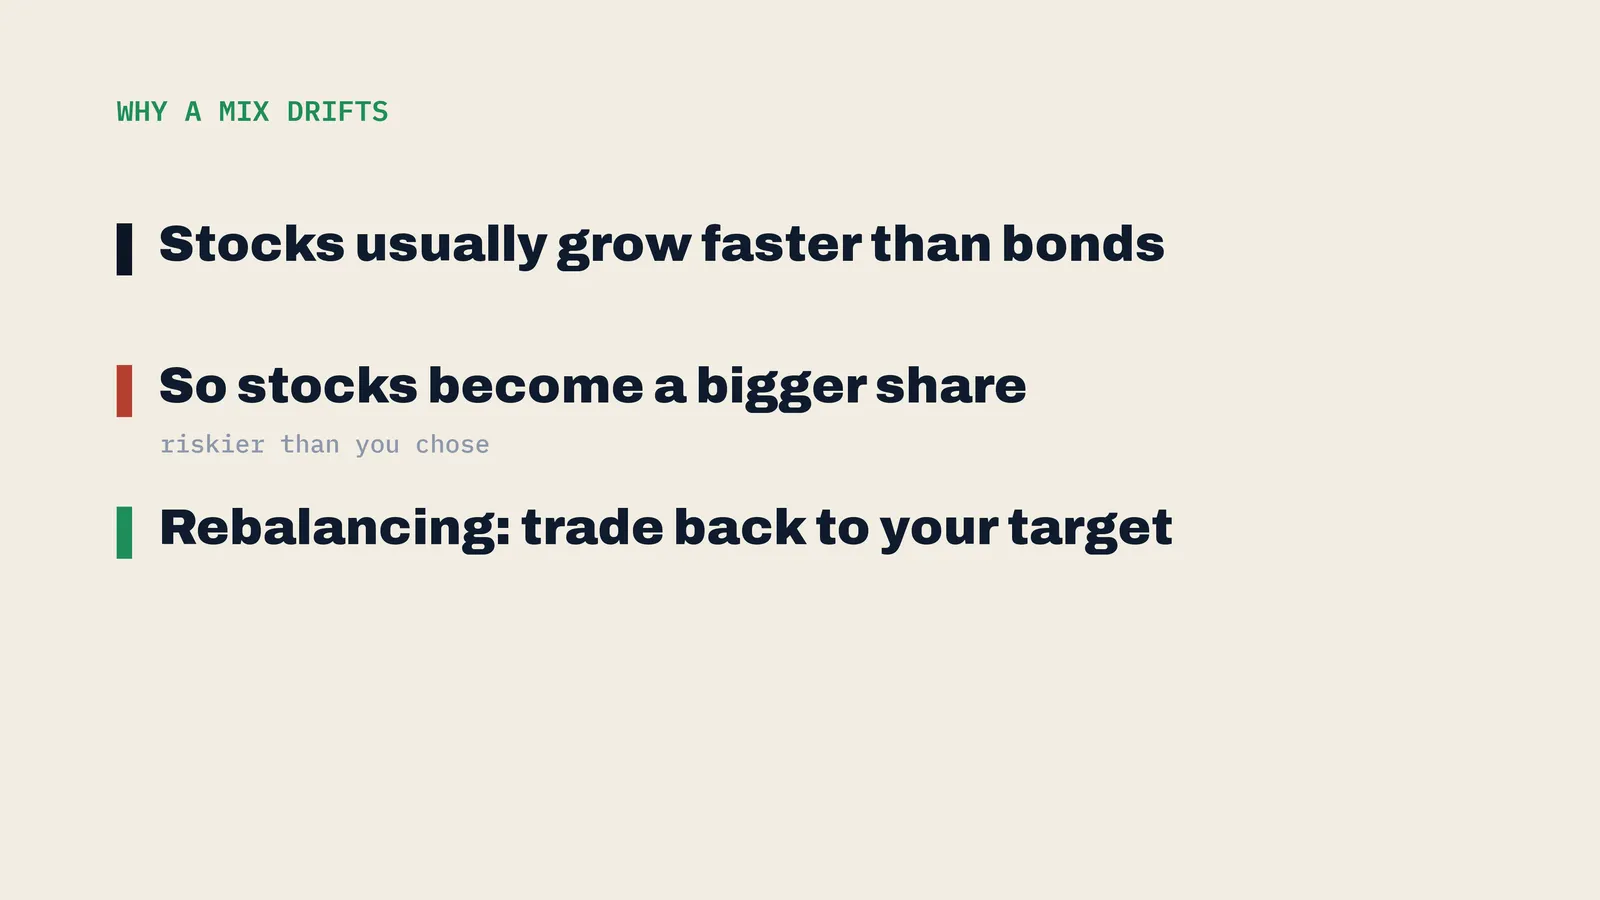
Stocks usually grow faster than bonds. Leave a mix alone, and stocks become a bigger share than you planned. The portfolio gets riskier than you chose. Rebalancing means trading back to your target.
| A 60/40 mix, never rebalanced (stocks 8%, bonds 4%) | Stocks |
|---|---|
| After 10 years | 69.1% |
| After 20 years | 76.9% |
Her mom’s IRA today
| Fund | Value | Target | Now | Off by | Trade |
|---|---|---|---|---|---|
| VTI (U.S. stocks) | $58,000 | 50% | 58% | +8 pts | Sell $8,000 |
| VXUS (international) | $12,000 | 10% | 12% | +2 pts | Sell $2,000 |
| BND (bonds) | $30,000 | 40% | 30% | −10 pts | Buy $10,000 |
| Total | $100,000 |
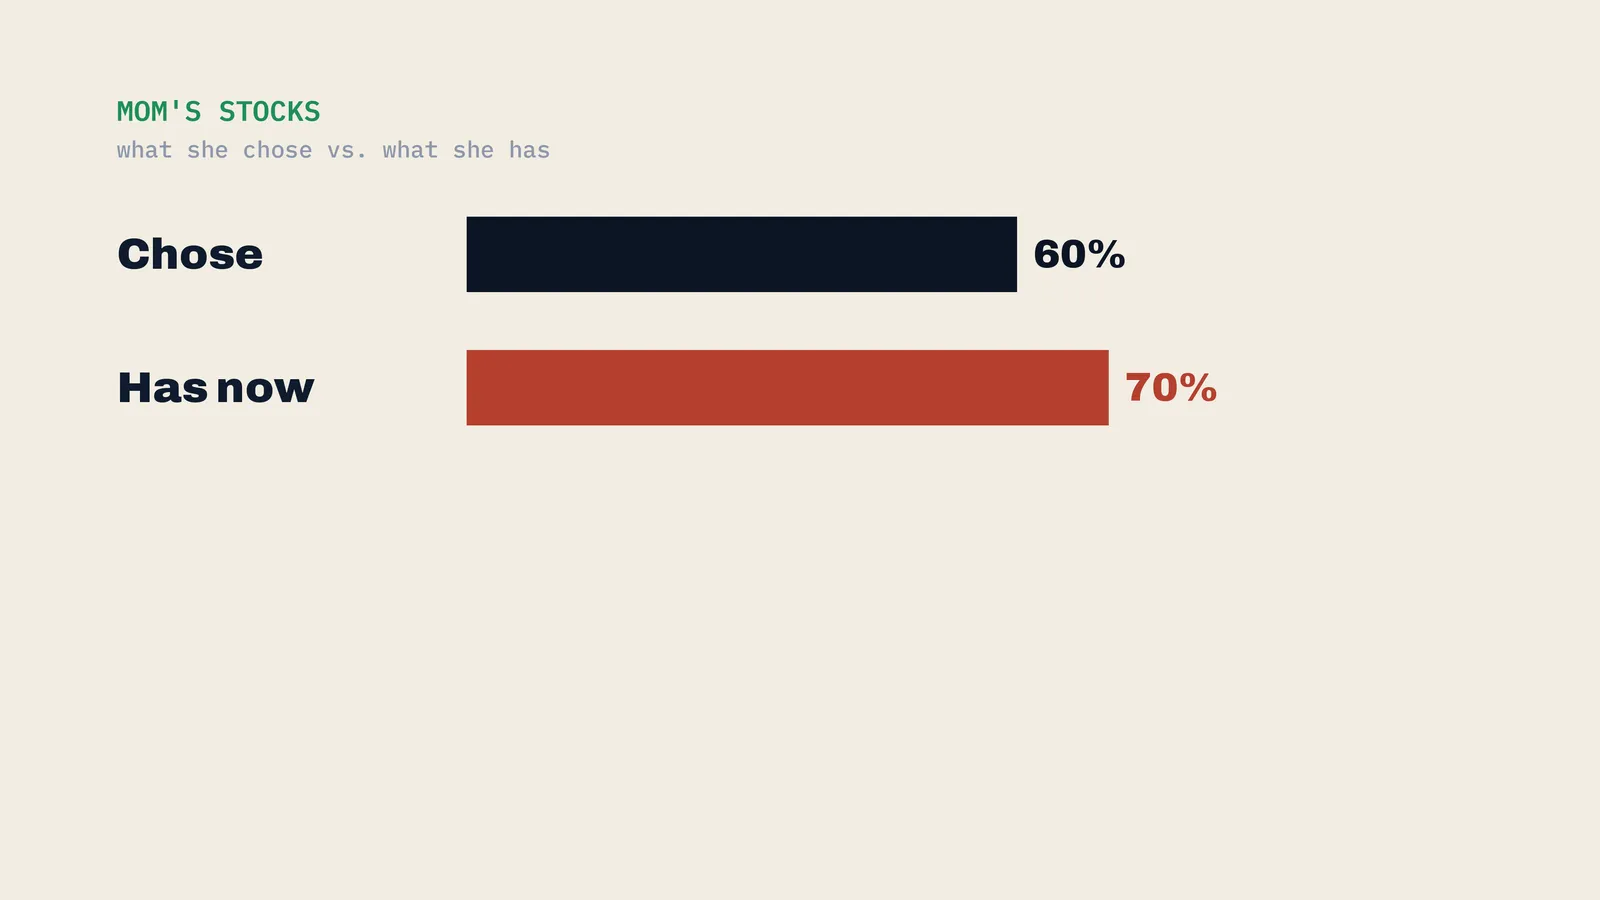
Stocks are now 70%, not 60%. Two funds cross the 5-point line: VTI and BND need trades. VXUS is only 2 points over, so its trade is optional: skip it, and the $8,000 VTI sale goes into BND, leaving BND at 38% and VXUS at 12%, both inside the line. Inside an IRA, these trades aren’t taxed.
Why it matters at 62
Remember Episode 12: a big drop right before or right after you retire does the most damage. Seventy percent stocks is more risk than her mom signed up for.
The Honest Check: 6% stocks, 3% bonds
Slower growth means slower drift, but it still drifts. Twenty years at 6% and 3%: 73.2% stocks instead of 60%. Rebalancing isn’t about earning more. It’s about keeping the risk you chose.
How often?
- Check once or twice a year.
- Rebalance when any fund is 5 points off its target.
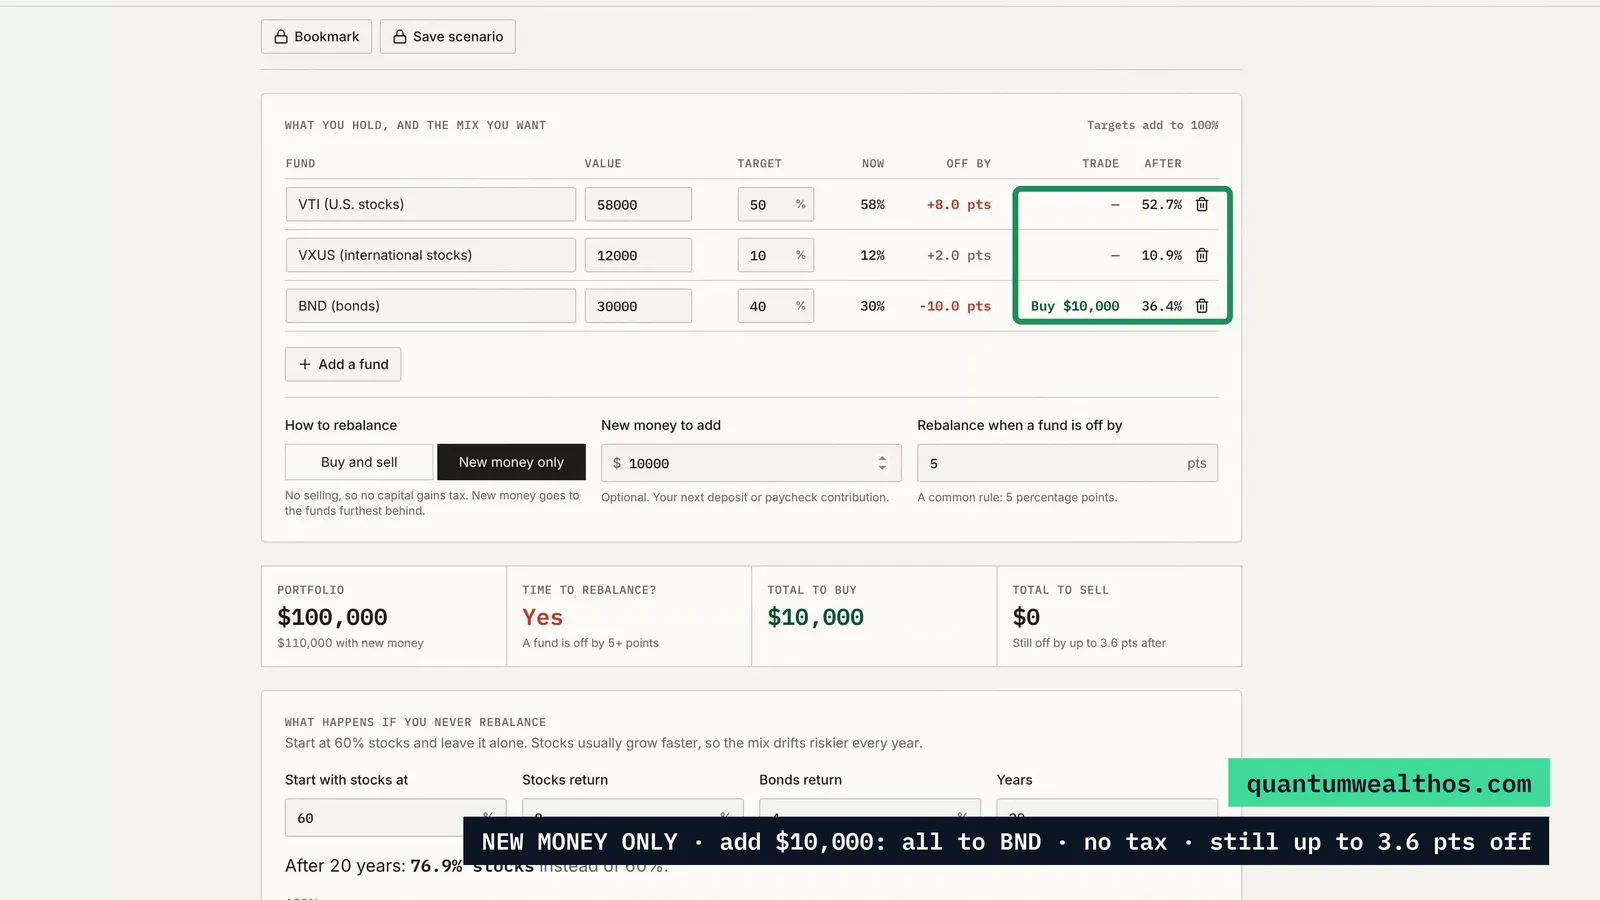
- In a taxable account, try new money first. With $10,000 of new money and no selling, all of it goes to BND, the fund furthest behind. That gets her closer (52.7% / 10.9% / 36.4%), but still up to about 3.6 points off.
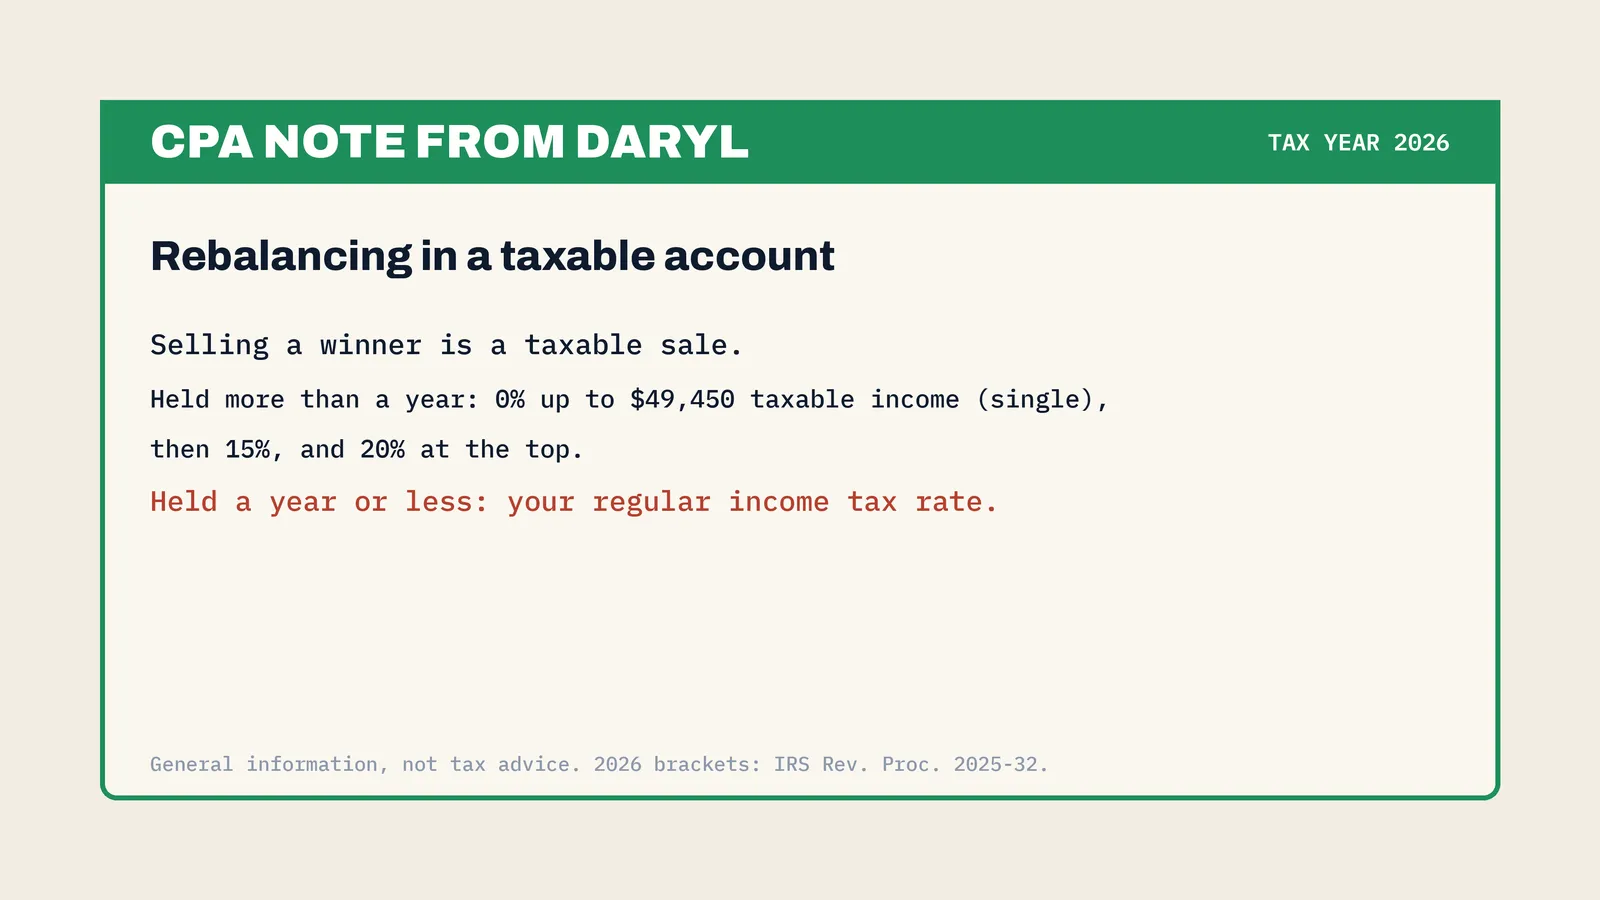
CPA Note from Daryl (tax year 2026)
In a regular brokerage account, selling a winner is a taxable sale.
- Held more than a year: long-term rates. 0% up to $49,450 of taxable income for single filers ($98,900 married filing jointly), then 15%, and 20% at the top.
- Held a year or less: taxed at your regular income tax rate.
- Send new money and dividends to the fund that’s behind to rebalance without selling.
Next up: can dividends pay your bills? SCHD, the dividend ETF.
How the math works
All figures come from the QWOS Rebalancing Calculator: holdings VTI $58,000, VXUS $12,000, BND $30,000 with targets of 50%, 10% and 40%; a 5-point threshold; “New money only” with $10,000; and the never-rebalance demo starting at 60% stocks with stocks at 8% and bonds at 4% (or 6% and 3%) for 10 or 20 years. Steady returns for illustration. 2026 capital gains brackets: IRS Rev. Proc. 2025-32.
Education, not financial or tax advice. Funds named are examples, not recommendations.