



Denise is 45, and she has a dream a lot of people share: retire on dividends. Never sell a share. Just let the checks pay the bills.
Meet SCHD
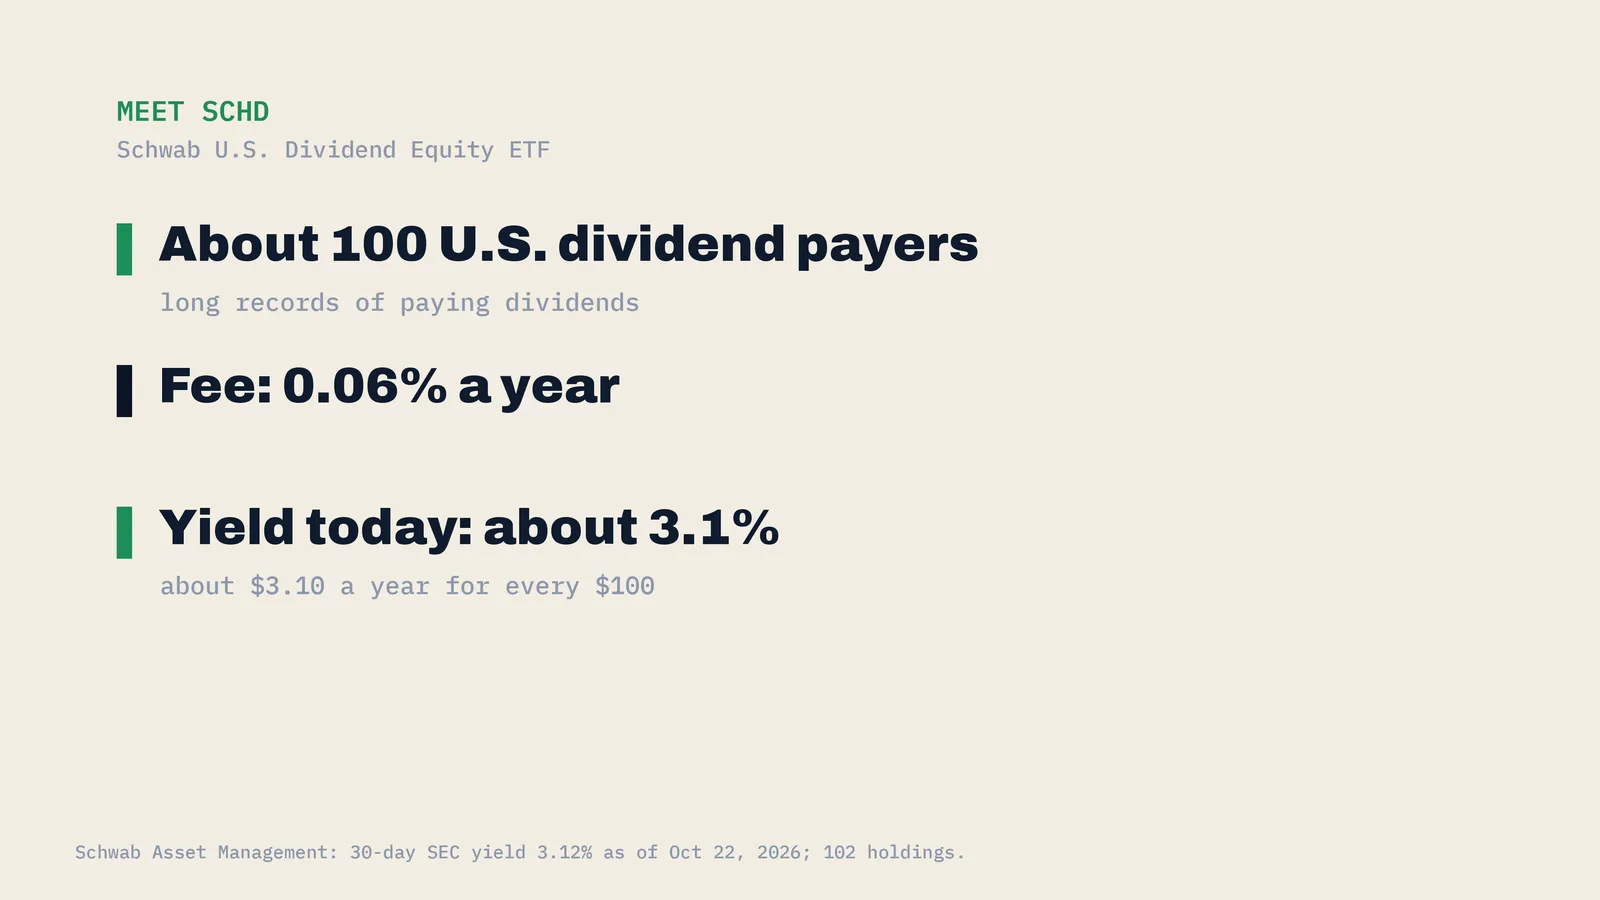
The fund people usually mean is SCHD, Schwab’s U.S. Dividend Equity ETF.
| SCHD | |
|---|---|
| What it holds | About 100 U.S. companies with long dividend records |
| Fee | 0.06% a year |
| Yield today | About 3.1% (30-day SEC yield 3.12%, Oct 22, 2026) |
That’s about $3.10 a year for every $100 invested.
How big a pile?
Denise wants dividends to cover $2,000 a month, $24,000 a year, on top of Social Security.
| To cover $24,000 a year | Portfolio needed |
|---|---|
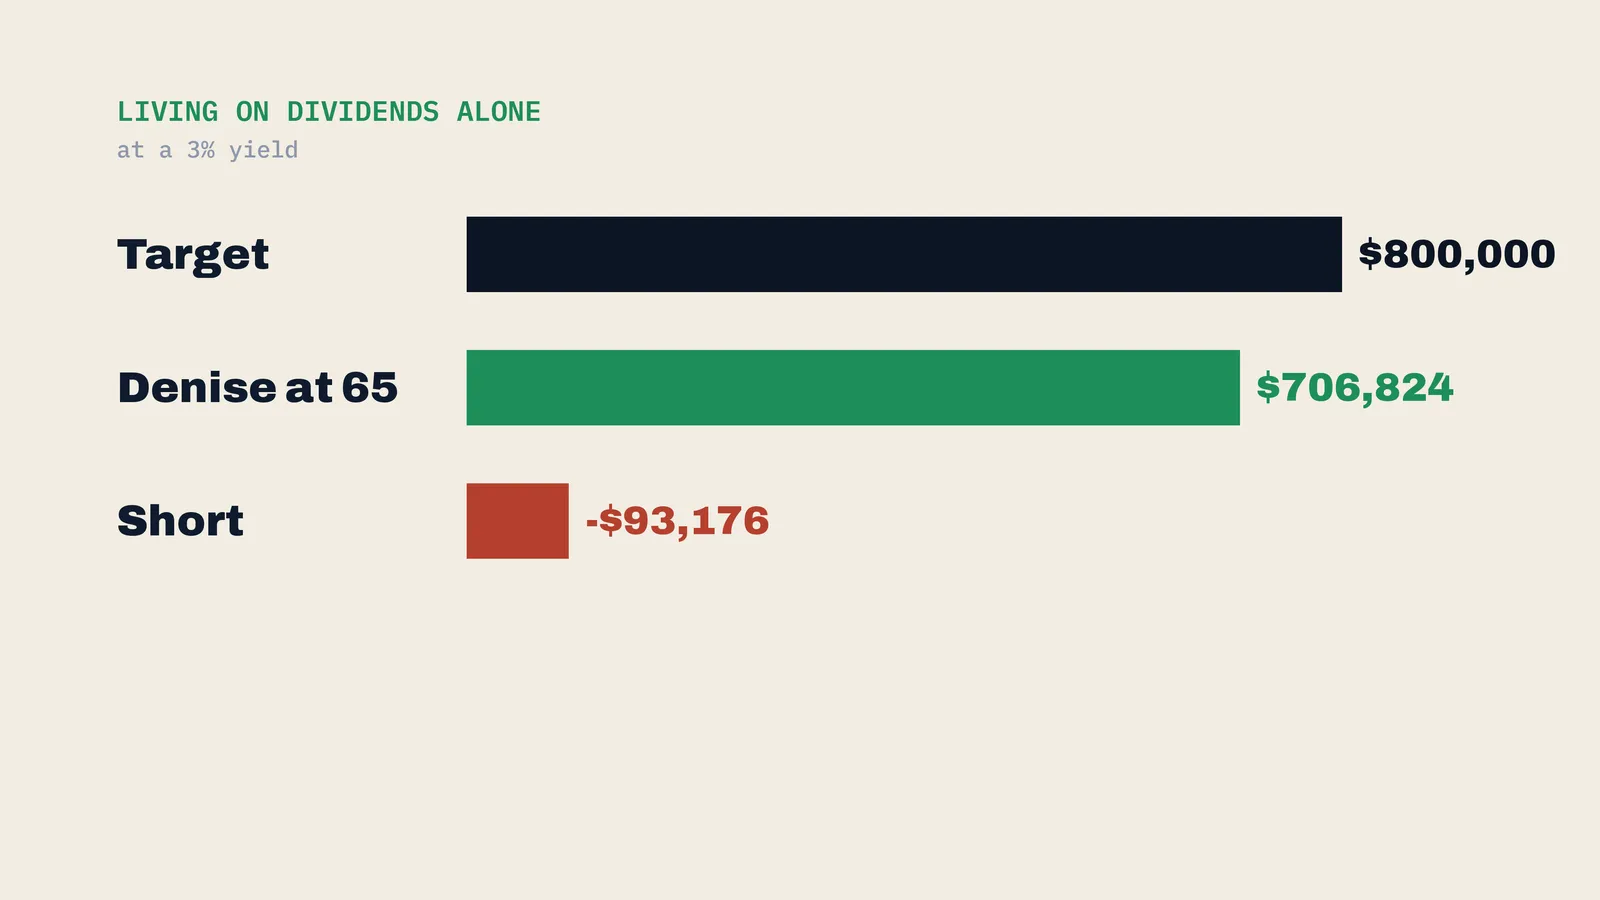
| Dividends alone, 3% yield | $800,000 |
| The 4% rule (Episode 10) | $600,000 |
Denise’s plan
Her plan from Episode 9: $1,200 a month from 45 to 65 at 8%.
| At 8% | |
|---|---|
| 45 to 65 (20 years) | $706,824 |
| Short of $800,000 | -$93,176 |
| 45 to 67 (22 years) | $860,146 |
Two more years and the dividends can cover it.
The catch: a dividend isn’t free money
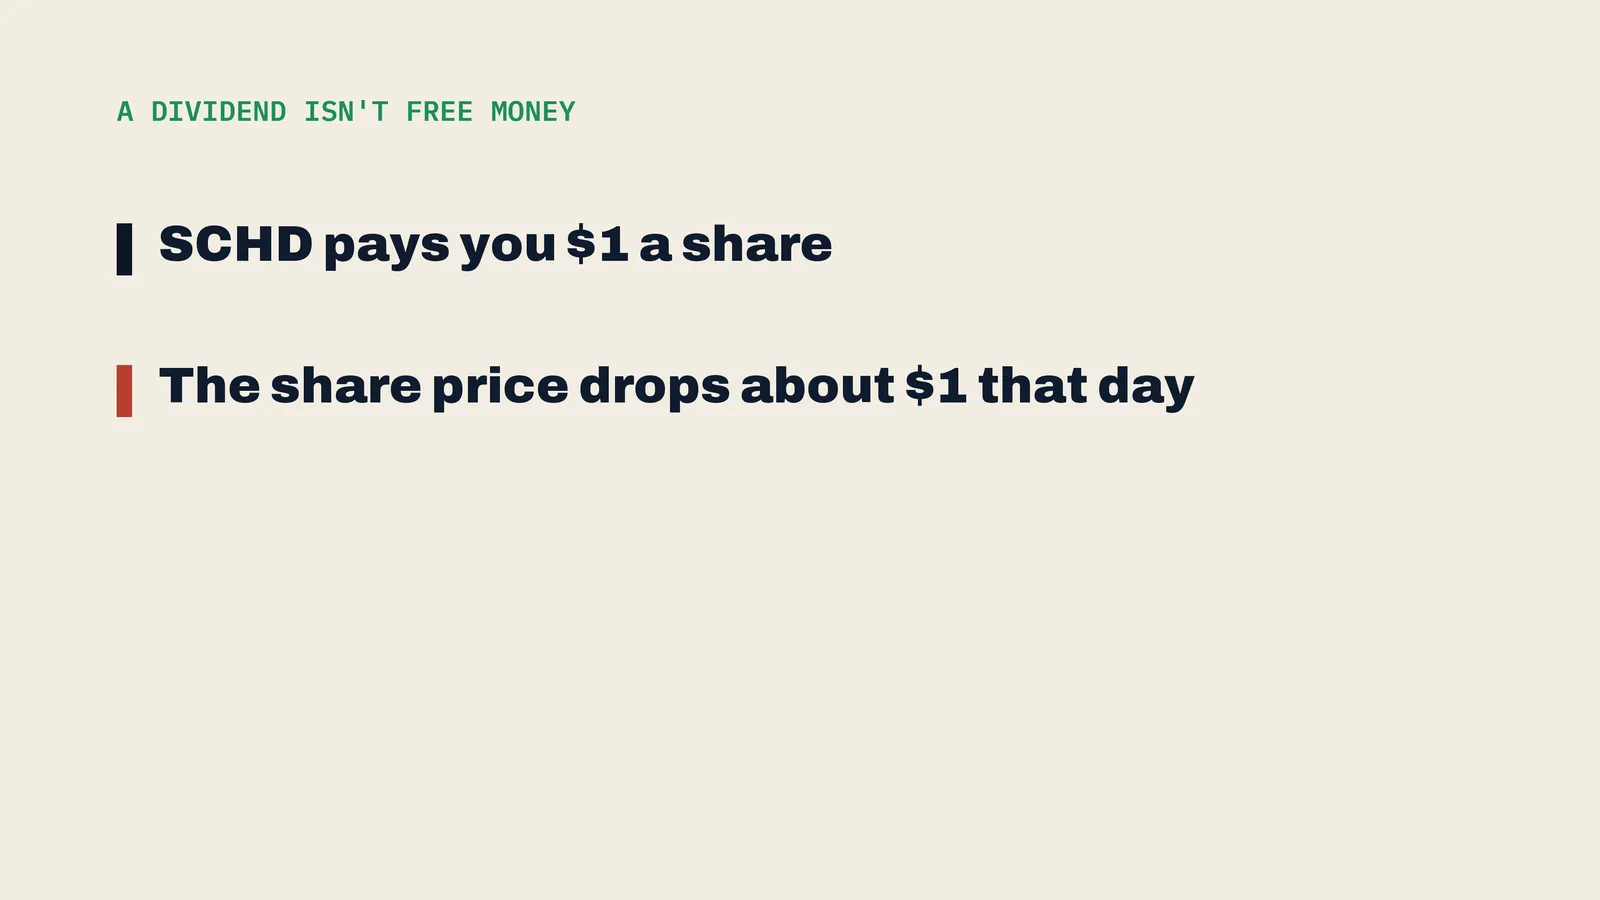
When SCHD pays you $1 a share, the share price drops by about $1 that day. What counts is total return: dividends plus price.
| Published 10-year return (as of Sep 30, 2026) | Per year |
|---|---|
| SCHD | 12.44% |
| VOO | 15.29% |
Past returns, not a forecast. Dividends are one way to get paid, not a better return.
The Honest Check: 6%
At 6%, 20 years of $1,200 a month is $554,449, about $246,000 short of the $800,000 dividend target. Living on dividends alone takes a bigger pile than most people think.
The plan
- Grow with a core fund (like VOO or VTI) while you’re working.
- Add SCHD for income as you get close.
- Remember you’re allowed to sell shares. The 4% rule needs a smaller pile than dividends alone.
CPA Note from Daryl (tax year 2026)
In a regular brokerage account, dividends are taxed every year, even if you reinvest them. Qualified dividends get the lower long-term rates: 0% up to $49,450 of taxable income for single filers ($98,900 married filing jointly), then 15%. Inside an IRA or a Roth, there’s no tax each year.
Next up: the earliest head start there is, a Roth IRA for your kid.
How the math works
Portfolio targets come from the QWOS FIRE Calculator ($24,000 a year; 3% and 4% withdrawal rates). Growth figures come from the QWOS Compound Interest Calculator ($1,200 a month; 20 or 22 years; 8% or 6%, compounded monthly). Published returns come from the QWOS ETF Growth Calculator. Yield: Schwab Asset Management. Tax brackets: IRS Rev. Proc. 2025-32.
Education, not financial or tax advice. Hypothetical returns; real results vary and losses happen.