



Denise searched for the average net worth at 45 and got a number that made her stomach drop: over a million dollars. Is she behind? Let’s run the real numbers.
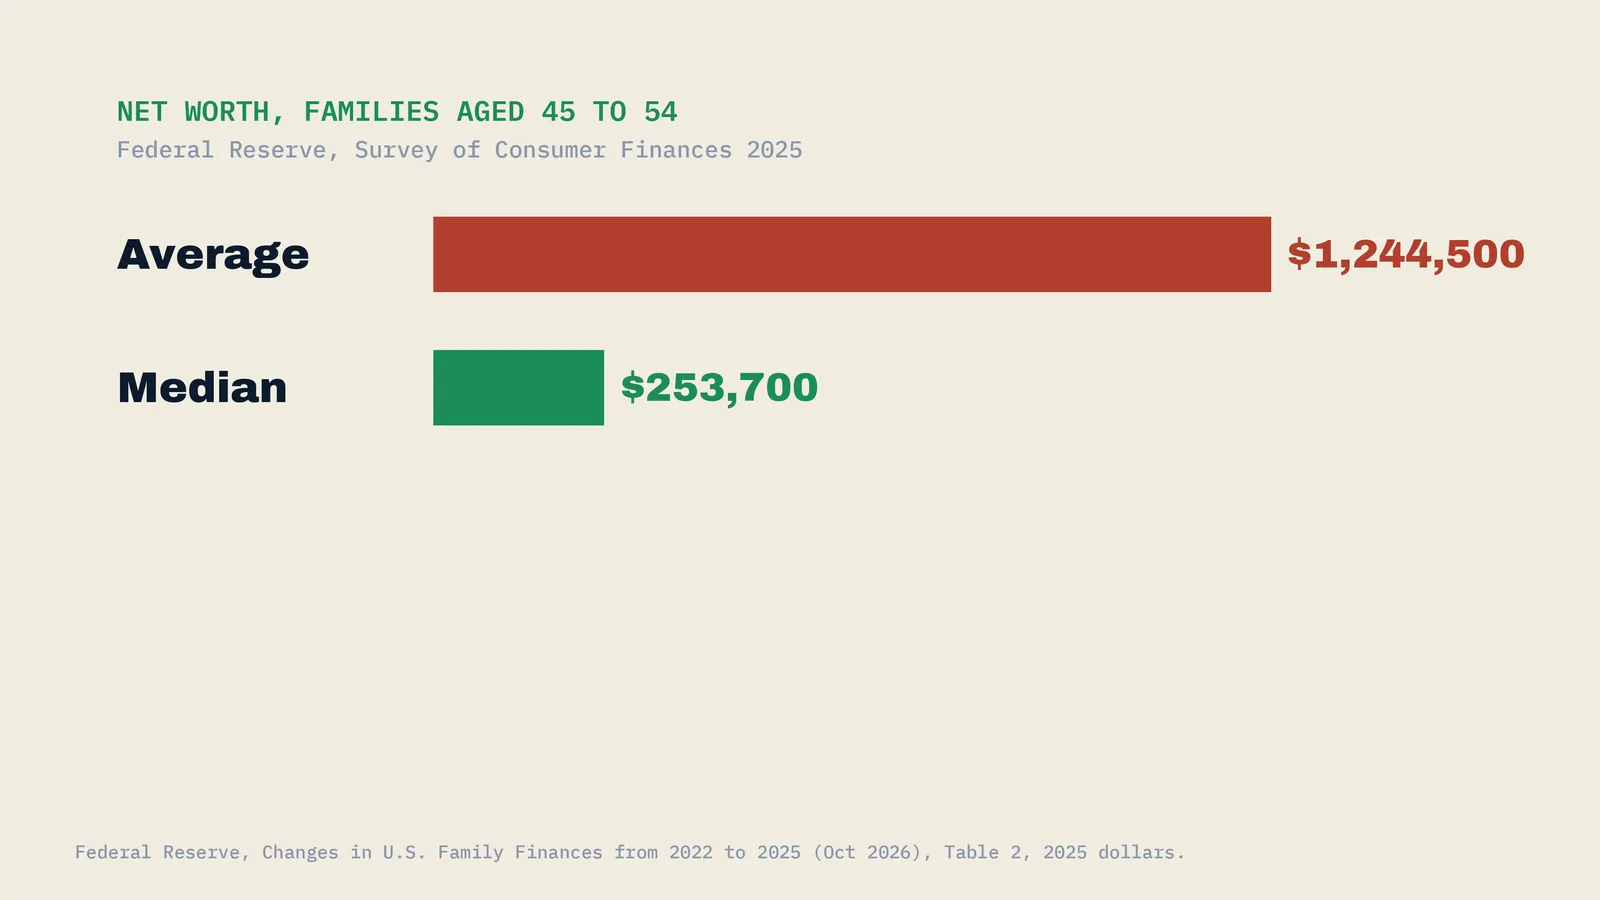
Average vs. median
| Net worth, families aged 45 to 54 (2025) | |
|---|---|
| Average (mean) | $1,244,500 |
| Median | $253,700 |
A few very wealthy families pull the average way up. The median is the family right in the middle: half of families that age have less.
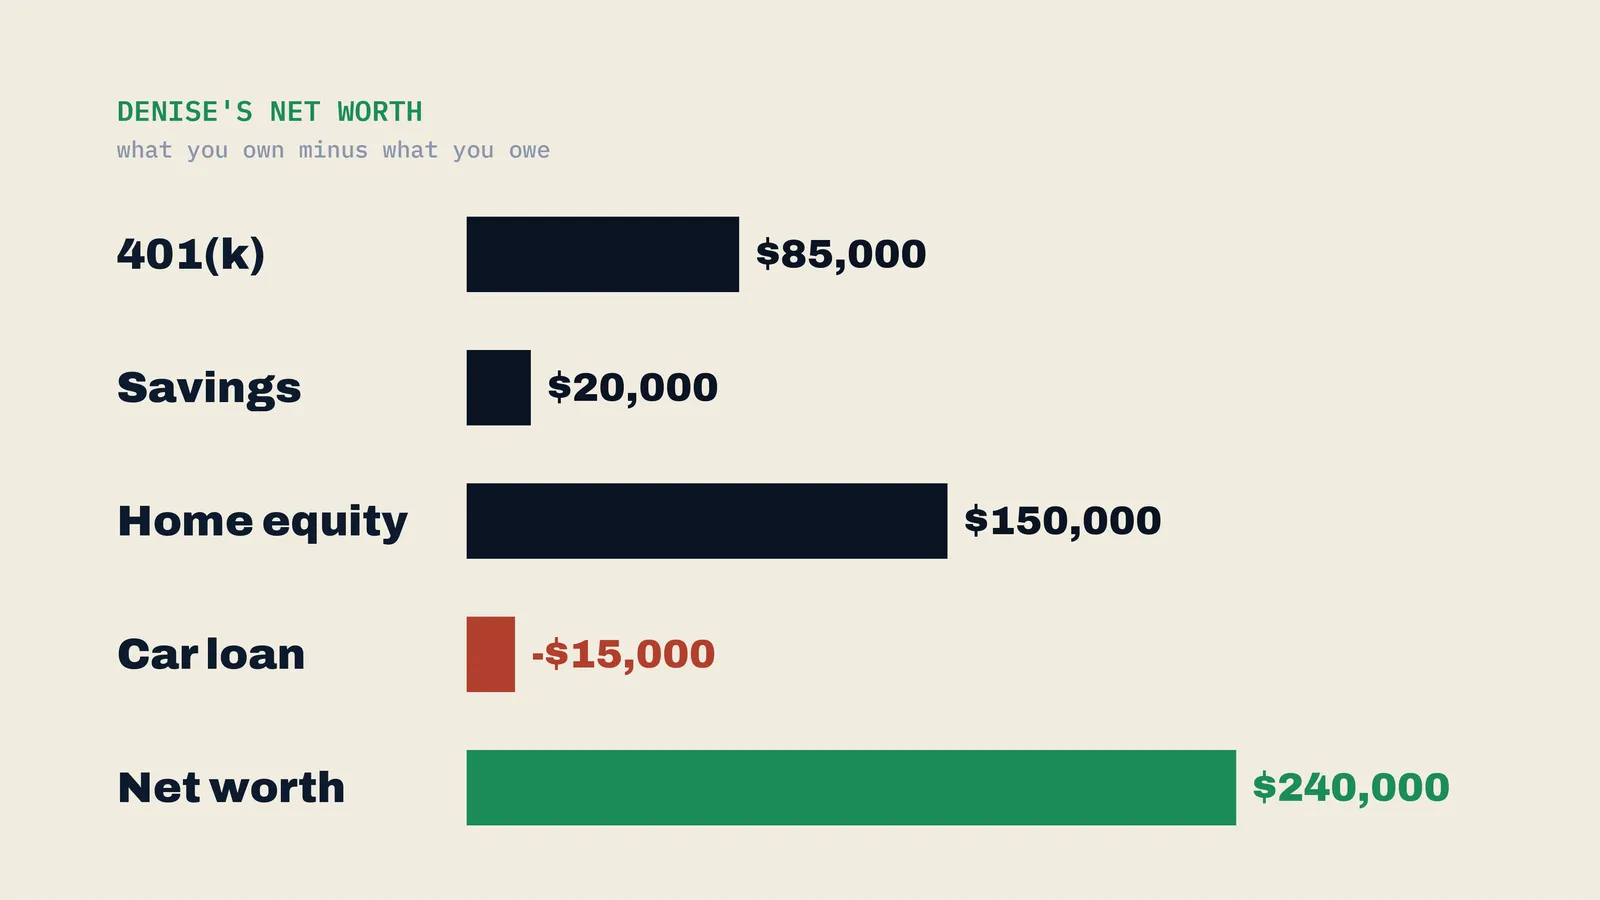
Denise’s net worth
| What she owns and owes | |
|---|---|
| 401(k) | $85,000 |
| Savings | $20,000 |
| Home equity | $150,000 |
| Car loan | −$15,000 |
| Net worth | $240,000 |
Right around the middle for her age.
Which way is it moving?
On the Net Worth Momentum tracker: $205,000 a year ago, $240,000 now. She saved $19,600 and paid her car loan down $6,000. Up $35,000. Accelerating. About $26,000 came from her own saving and paydown, about $9,000 from growth.
Fidelity’s yardstick
Fidelity suggests 3x your salary by 40 and 6x by 50, so about 4.5x at 45. On $120,000, that’s about $540,000. Denise has $85,000 in retirement accounts. By that measure she’s behind, but the guideline assumes saving 15% from 25 and retiring at 67. So check her actual plan.
Her actual plan
| Retirement calculator: 45 to 67, $85,000 saved, 8%, 3% inflation, $70,000 a year of spending, $2,800/mo Social Security | At 67 | Status |
|---|---|---|
| $1,300 a month (10% + $300 match) | $1,423,005 | Short $320,650 |
| $1,500 a month (12%) | $1,566,362 | Short $177,292 |
| $1,750 a month | $1,745,559 | On track |
Her target, using the 4% rule: $1,743,654. Her gap isn’t a million dollars. It’s about $447 a month, the calculator says. At 50, the 401(k) catch-up gives her more room (Episode 28).
The Honest Check: 6%
| At 6% | At 67 | Gap |
|---|---|---|
| 10% plan | $1,027,240 | $716,414 short |
| $1,750 a month | $1,273,041 | $470,613 short |
At 6%, she’d need to save more, retire a little later, or plan to spend less. The gap tells her which levers to watch.
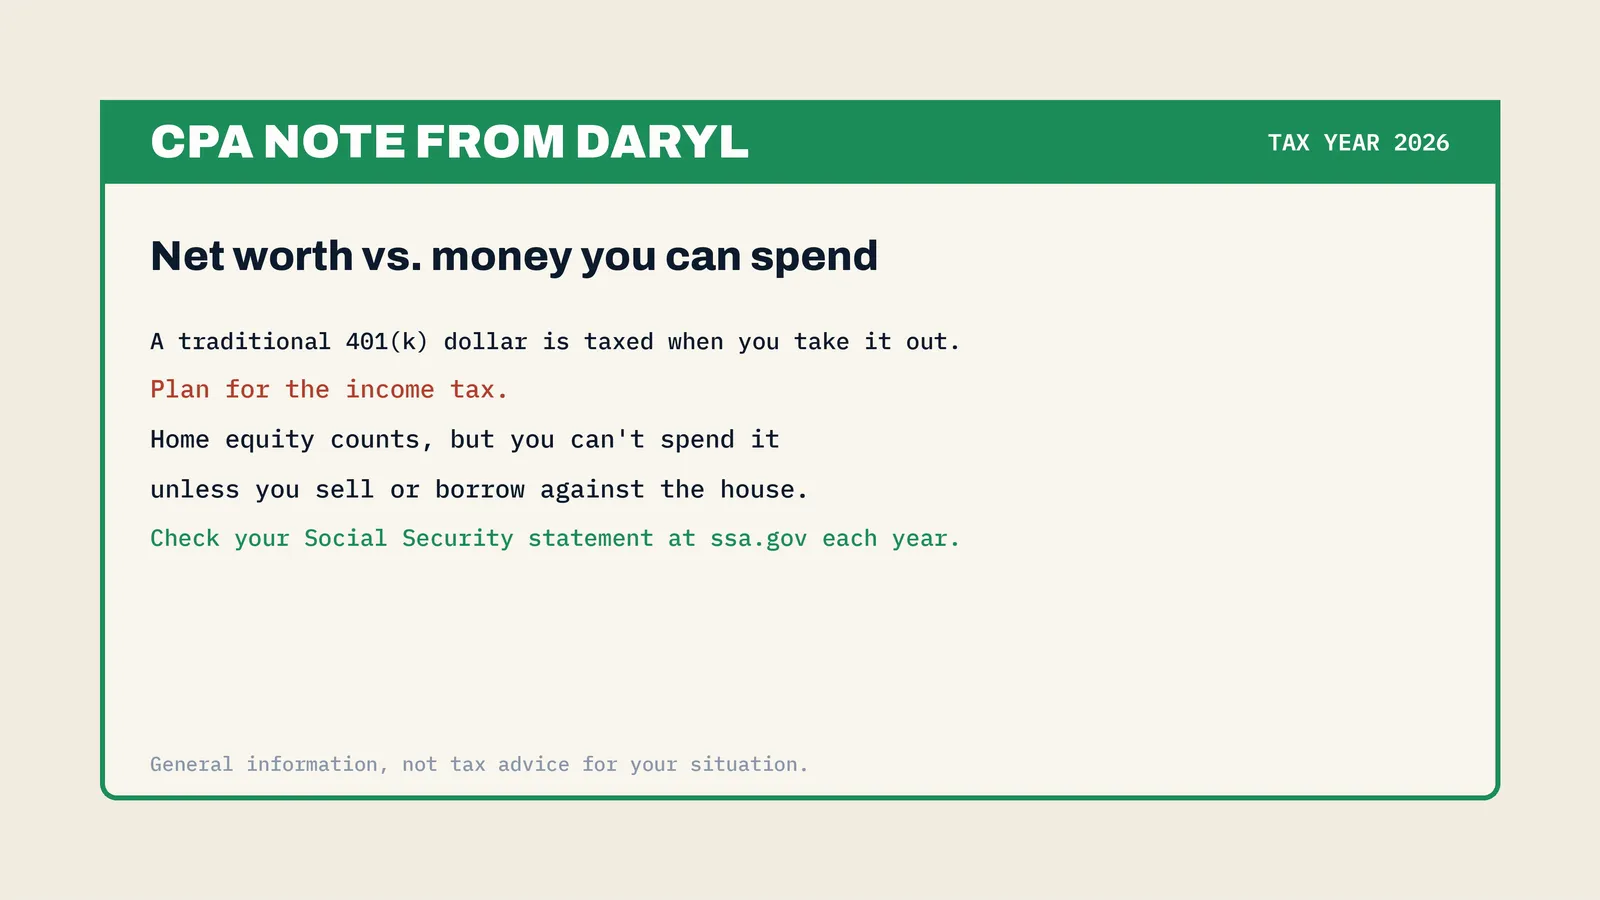
CPA Note from Daryl (tax year 2026)
- A dollar in a traditional 401(k) isn’t a dollar to spend. You’ll pay income tax when you take it out.
- Home equity counts in net worth, but you can’t spend it unless you sell or borrow against the house.
- Check your Social Security statement at ssa.gov each year. Your benefit is based on your earnings history.
Next up: the buy now, pay later trap.
How the math works
Net worth: Federal Reserve, Changes in U.S. Family Finances from 2022 to 2025 (October 2026), Table 2, 2025 dollars. Momentum: QWOS Net Worth Momentum Tracker. Retirement: QWOS Retirement Calculator (age 45, retire 67, life expectancy 90, $85,000 saved, 3% inflation, $70,000 a year in today’s dollars, $2,800 a month Social Security in today’s dollars). Guideline: Fidelity Viewpoints, “How much do I need to retire?”
Education, not financial or tax advice. Hypothetical returns; real results vary and losses happen.