



Maya’s December cart: sneakers, headphones, a jacket. At checkout, the button says: pay in 4, no interest. Then a new laptop on a 12-month plan. Each one feels small.
How common it is
In LendingTree’s 2026 survey of buy now, pay later users:
- 47% paid late on at least one loan in the past year (up from 41% in 2025)
- 25% have had three or more loans going at once
- 29% have used it for groceries
Maya’s stack
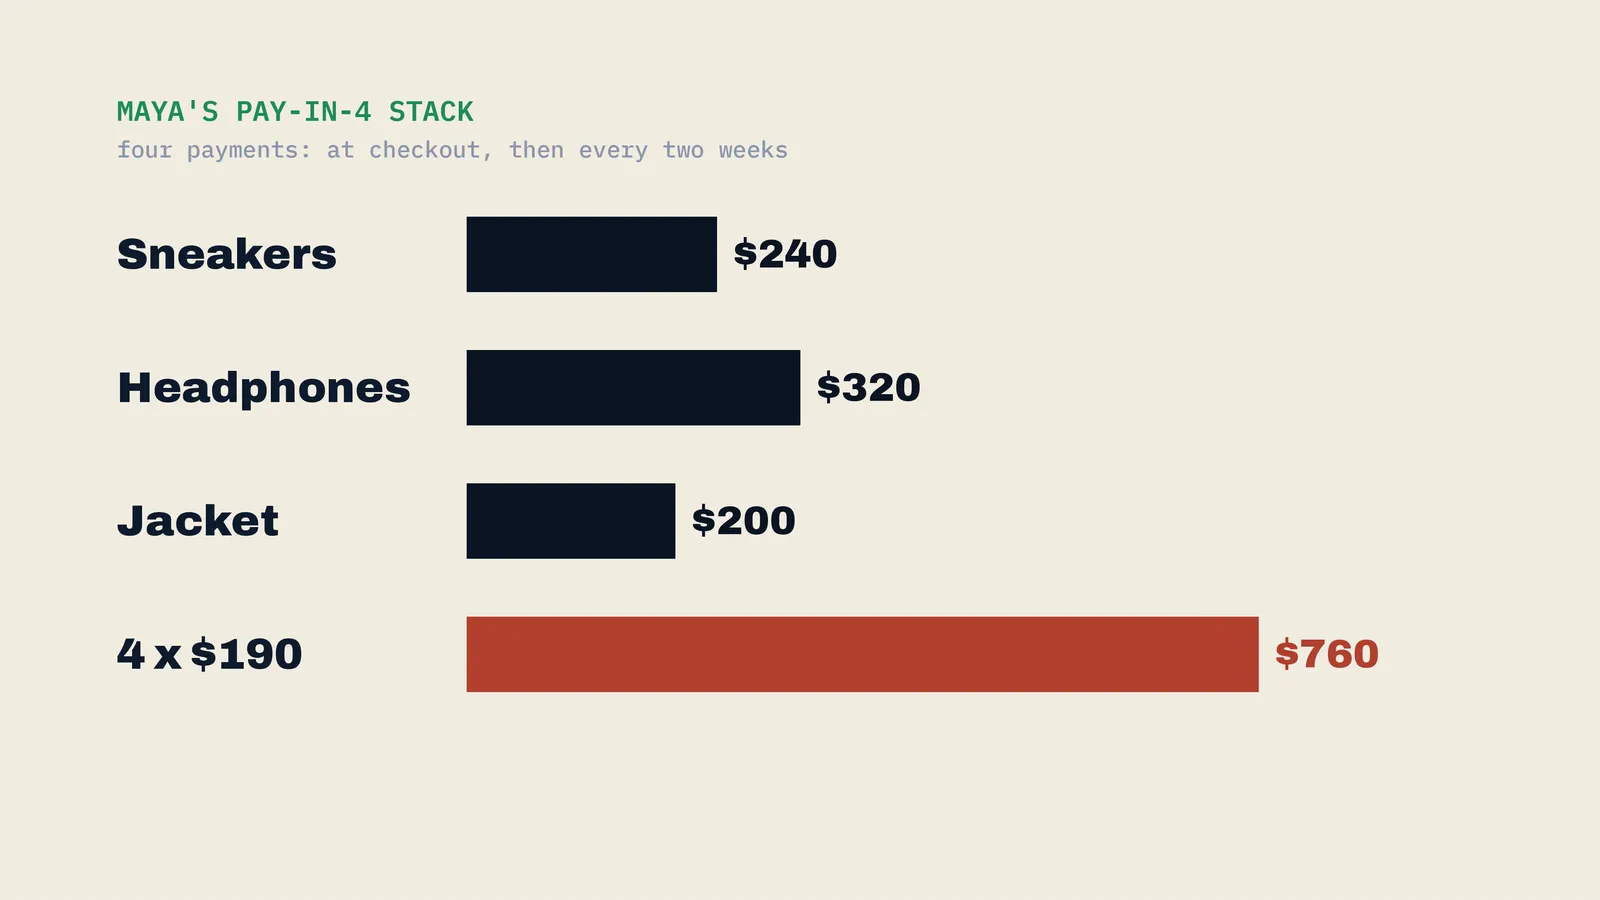
| Pay in 4 | |
|---|---|
| Sneakers | $240 |
| Headphones | $320 |
| Jacket | $200 |
| Total | $760: four payments of $190, at checkout and then every two weeks |
The laptop plan isn’t interest-free. Some monthly plans charge up to 36%.
| Loan calculator: $1,200, 30% APR, 12 months | |
|---|---|
| Monthly payment | $116.98 |
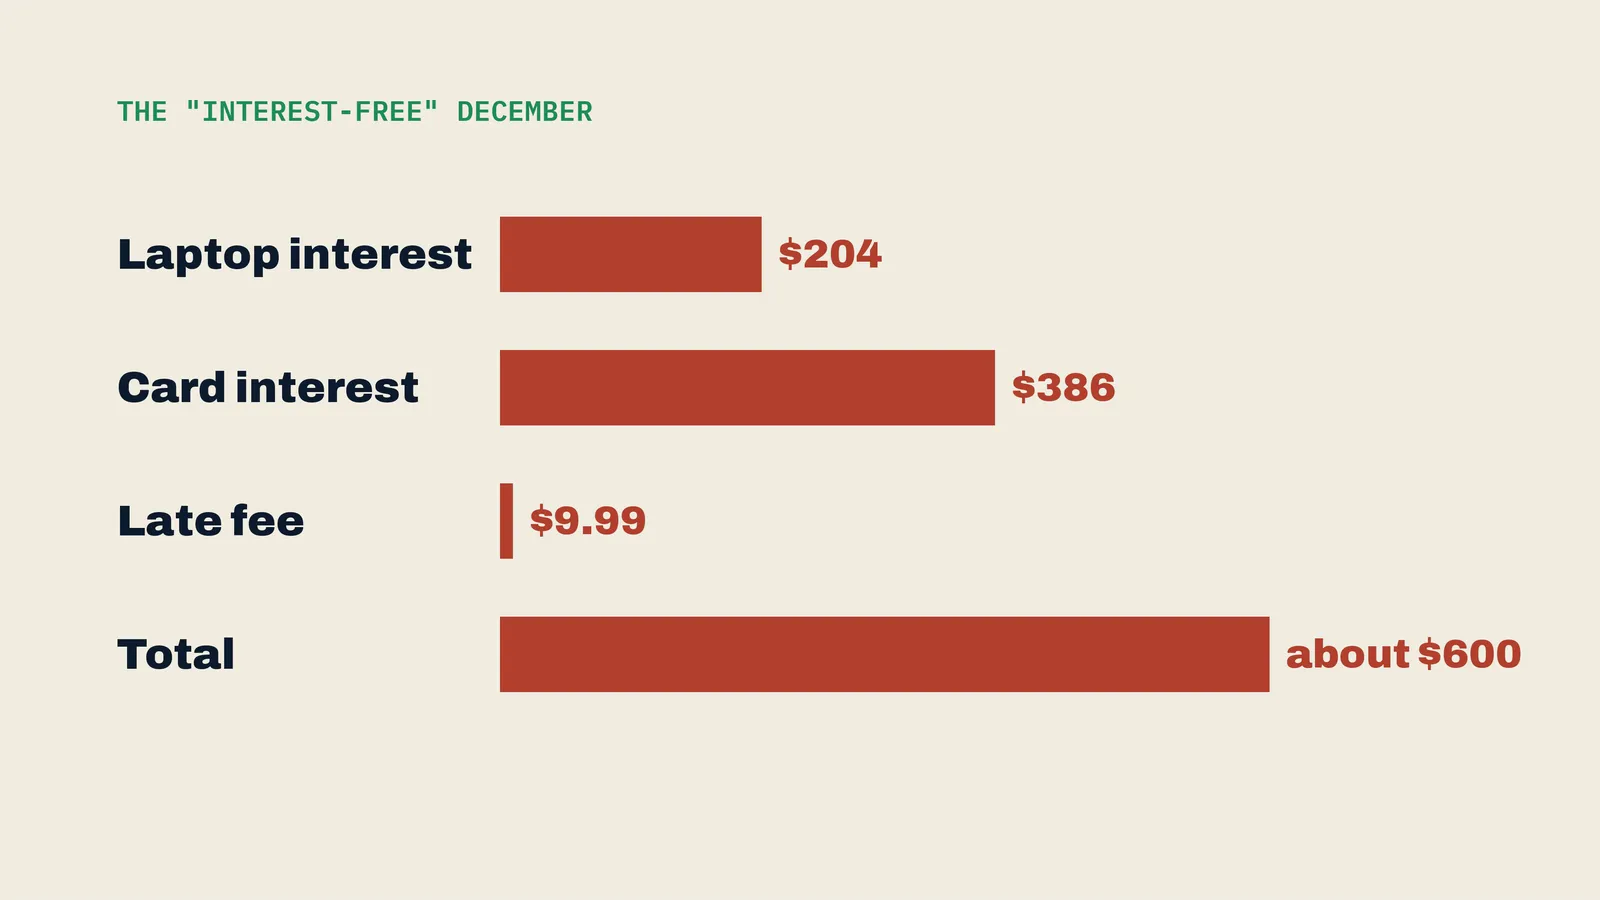
| Interest | $204 |
| Total | $1,404 |
Maya takes home $1,948 a paycheck. For the next few paychecks, about $250 of each one goes to things she already bought: roughly 1 dollar in 8.
January
One payment fails, and there’s a late fee. The CFPB found the average buy now, pay later late fee was $9.99 in 2023. Then Maya covers the gap with her credit card: $1,500 at 22%.
| Credit card calculator: $1,500, 22%, $75 a month | |
|---|---|
| Time to pay off | 2.2 years |
| Interest | $386 |
Add it up: $204 + $386 + the late fee = about $600 for a December that was supposed to be interest-free.
The other way: save first
$100 a month for a year at 4%, on the savings calculator: $1,222. That’s the laptop, paid in cash.
When buy now, pay later is okay
- One plan at a time
- Truly 0% interest
- Autopay from money that’s already in your checking account
- Never for things that are gone before the last payment, like groceries
The warning sign: paying for last month while buying this month.
The Honest Check: 6%
Say Maya invests $150 a month instead, from 31 to 65.
| Compound interest calculator | |
|---|---|
| At 8% | $315,988 |
| At 6% | $199,548 |
| Put in | $61,200 |
The debt side doesn’t depend on the market: $386 of card interest and $204 on the laptop at any return.
CPA Note from Daryl (tax year 2026)
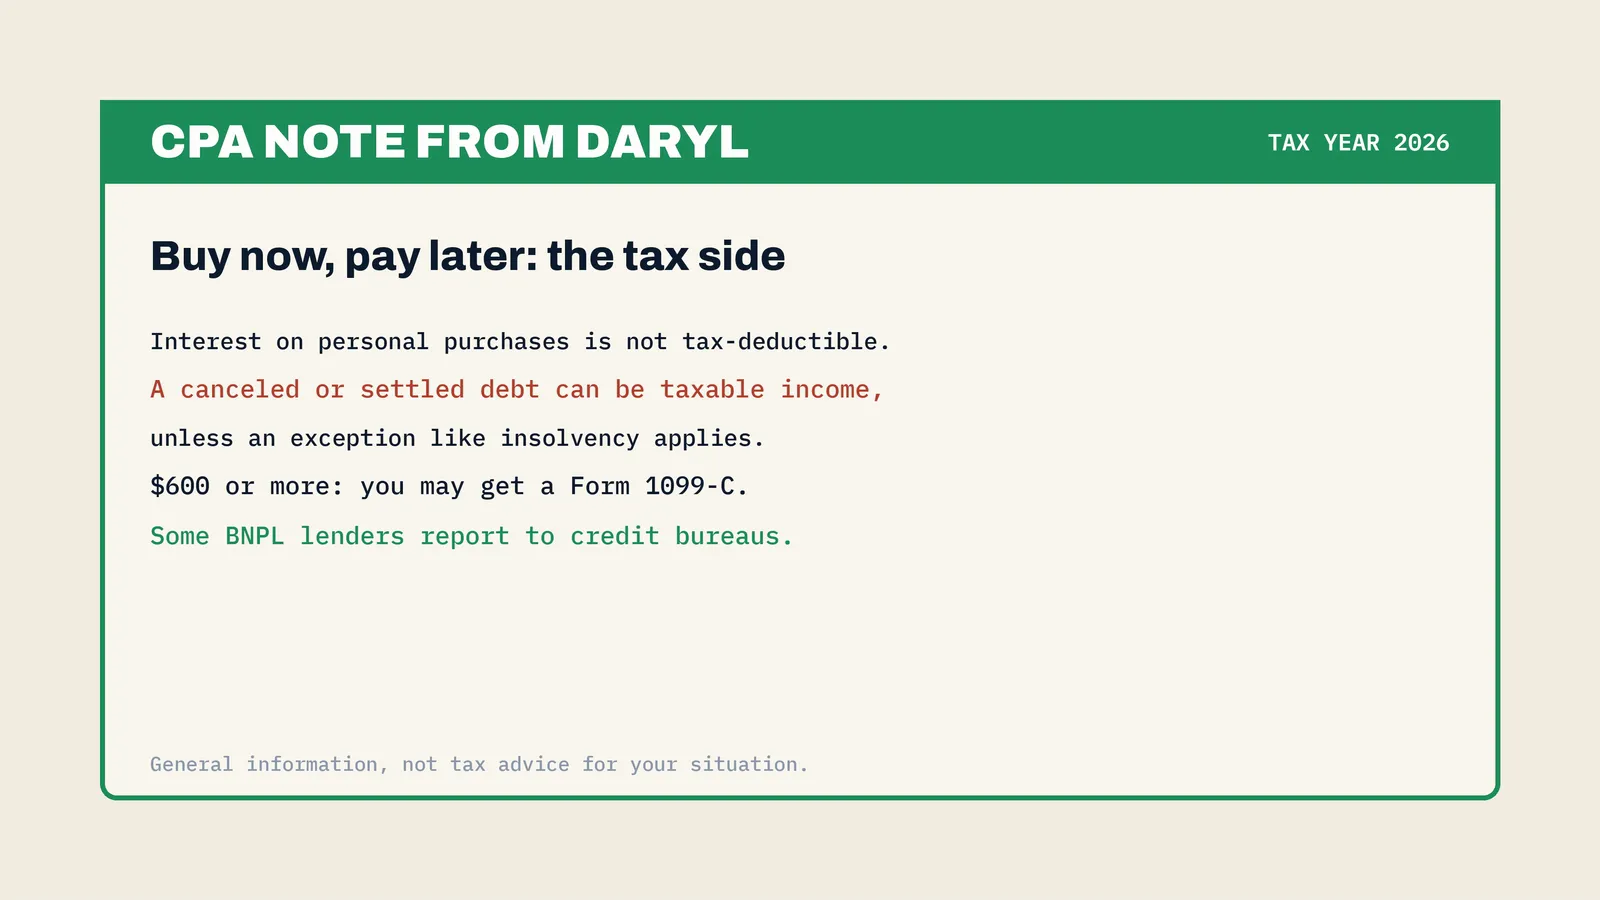
- Interest on personal purchases like a laptop plan or a credit card isn’t tax-deductible.
- If a lender cancels or settles a debt for less than you owe, the forgiven amount can count as taxable income, unless an exception like insolvency applies. For $600 or more, you may get a Form 1099-C.
- Some buy now, pay later lenders now report to credit bureaus, so late payments can follow you.
Next up: why two incomes can leave you more broke than one.
How the math works
Laptop: QWOS Loan Calculator ($1,200, 30% APR, 1 year). Card: QWOS Credit Card Payoff Calculator ($1,500, 22%, $75 fixed payment). Save first: QWOS Savings Calculator ($100 a month, 4%, 1 year). Invest instead: QWOS Compound Interest Calculator ($150 a month, 34 years). Take-home: Episode 30. Sources: LendingTree 2026 BNPL report; CFPB, The Buy Now, Pay Later Market (December 2025).
Education, not financial or tax advice. Hypothetical returns; real results vary and losses happen.