



Most money advice tells you what you’re doing wrong. This one checks what you might be doing right. Five signs, each with a real number.
Sign 1: you could handle a surprise bill without borrowing
In the Federal Reserve’s latest survey, 63% of adults said they would cover a $400 emergency with cash or its equivalent. The rest would have to borrow, sell something, or couldn’t pay at all.
Maya went further: three months of expenses. She spends $2,800 a month, so her target was $8,400.
| Savings calculator, 4% | |
|---|---|
| $350 a month, 2 years | $8,730 |
| Starting from zero: $100 a month, 1 year | $1,222 |
Sign 2: you get the full employer match
Marcus earns $100,000 and puts in 12%. His employer adds 50 cents per dollar on the first 6%: $250 a month.
| 401(k) calculator, 40 to 64, 8% | Match | Balance at 64 |
|---|---|---|
| 12% | $72,000 | $1,083,307 |
| Only 3% | $36,000 | $324,992 |
Sign 3: you save more than average
Among workers in Vanguard’s retirement plans, the average total savings rate (employee plus employer) was 12.1% in 2025. Denise puts in 10% of $120,000 and her match adds 3%: $1,000 + $300 a month, 13% in total. Raising her own share to 12% takes her 401(k) at 67 from $1,423,005 to $1,566,362 (Episode 28).
Sign 4: your net worth went up this year
Net worth is everything you own minus everything you owe. Check it once a year.
| Net Worth Momentum tracker | Maya |
|---|---|
| 12 months ago | $120,000 |
| Today | $146,400 |
| Saved this year | $16,800 |
| From investments | about $10,000 |
| Momentum | Accelerating (+$26K) |
If yours went down, look at why. A market drop usually passes. New debt can turn into a habit.
Sign 5: you don’t carry a credit card balance
Across card accounts that were charged interest, the average rate was about 22% (22.36%) in August 2026. On the debt payoff calculator, $3,000 at 22%, paying $150 a month, takes 2 years and 2 months and costs $771 in interest. Pay in full every month and that’s zero.
The Honest Check: 6%
| At 6% | |
|---|---|
| Marcus at 64 | $801,395 (match still $72,000) |
| Denise at 67, 12% | $1,136,485 (vs $1,027,240 at 10%) |
The rest are mostly habits, and a slower market doesn’t take those away.
Count yours
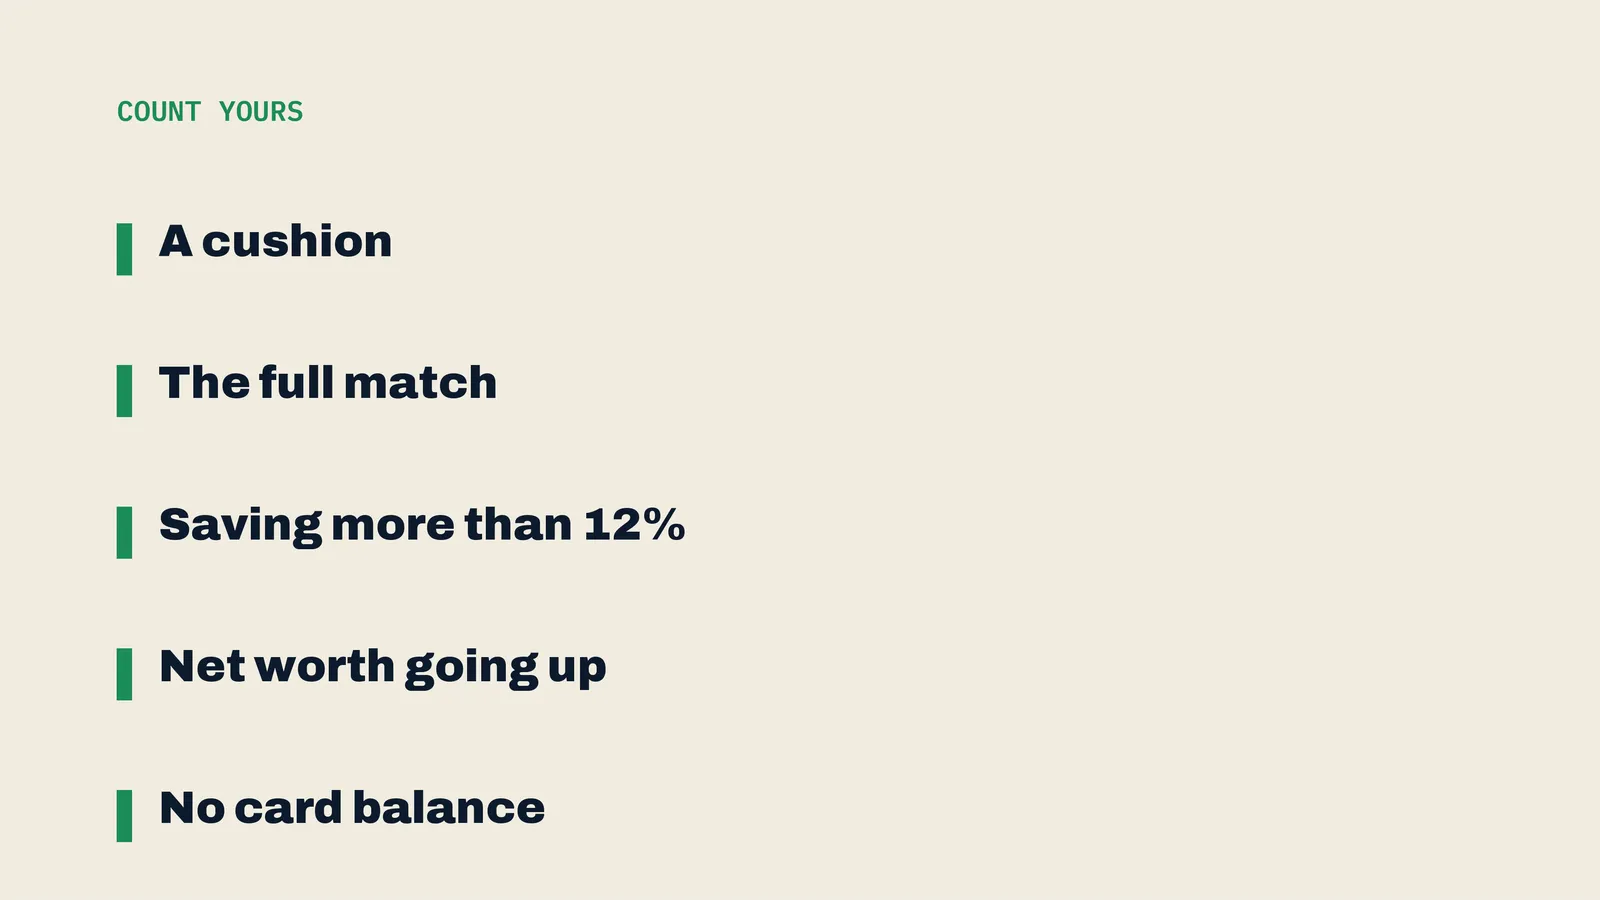
A cushion. The full match. Saving more than 12%. Net worth going up. No card balance. Three or more, and you’re probably doing better than you think. Zero? Start with the first one.
CPA Note from Daryl (tax year 2026)
- Interest on your savings account is taxable income, even if you never withdraw it. Your bank sends a 1099-INT when it’s $10 or more.
- Check your match’s vesting schedule. Leave before you’re vested and you can lose some or all of your employer’s money. Your own contributions are always yours.
Next up: the paycheck order, step by step.
How the math works
Savings: QWOS Savings Calculator (monthly deposits and compounding, 4%). 401(k): QWOS 401(k) Calculator ($0 balance, $100,000 salary, age 40, 24 years; Denise: $85,000, $120,000, age 45, 22 years; 50% match up to 6%; 8% or 6%). Net worth: QWOS Net Worth Momentum tracker. Card interest: QWOS Debt Payoff Calculator. Sources: Federal Reserve, Economic Well-Being of U.S. Households in 2025 (May 2026); Vanguard, How America Saves 2026; FRED series TERMCBCCINTNS.
Education, not financial or tax advice. Hypothetical returns; real results vary and losses happen.