



Maya opened her Roth IRA. Now her friends want one too. But a Roth comes with rules: you need the right kind of income, and not too much of it. Here’s who can.
Rule 1: earned income
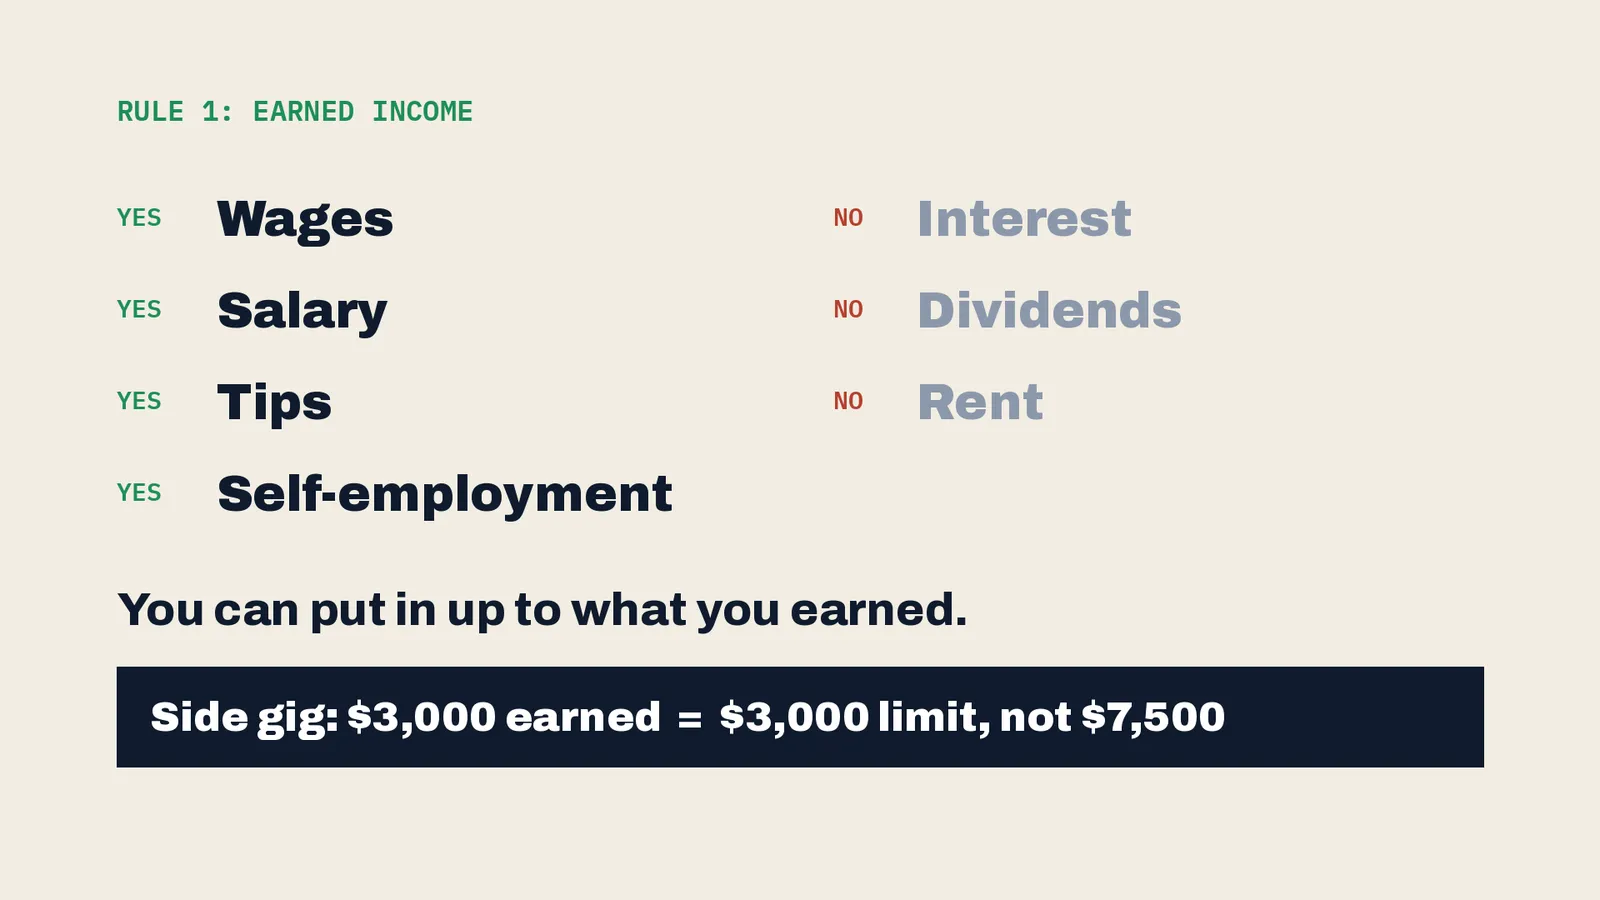
Wages, salary, tips and self-employment count. Interest, dividends and rent don’t. And you can only put in up to what you earned: earn $3,000 from a side gig and your limit is $3,000, not $7,500.
Even that counts. $3,000 a year from 25 to 65 could grow to $872,752 at 8%.
Rule 2: the income limits (2026)
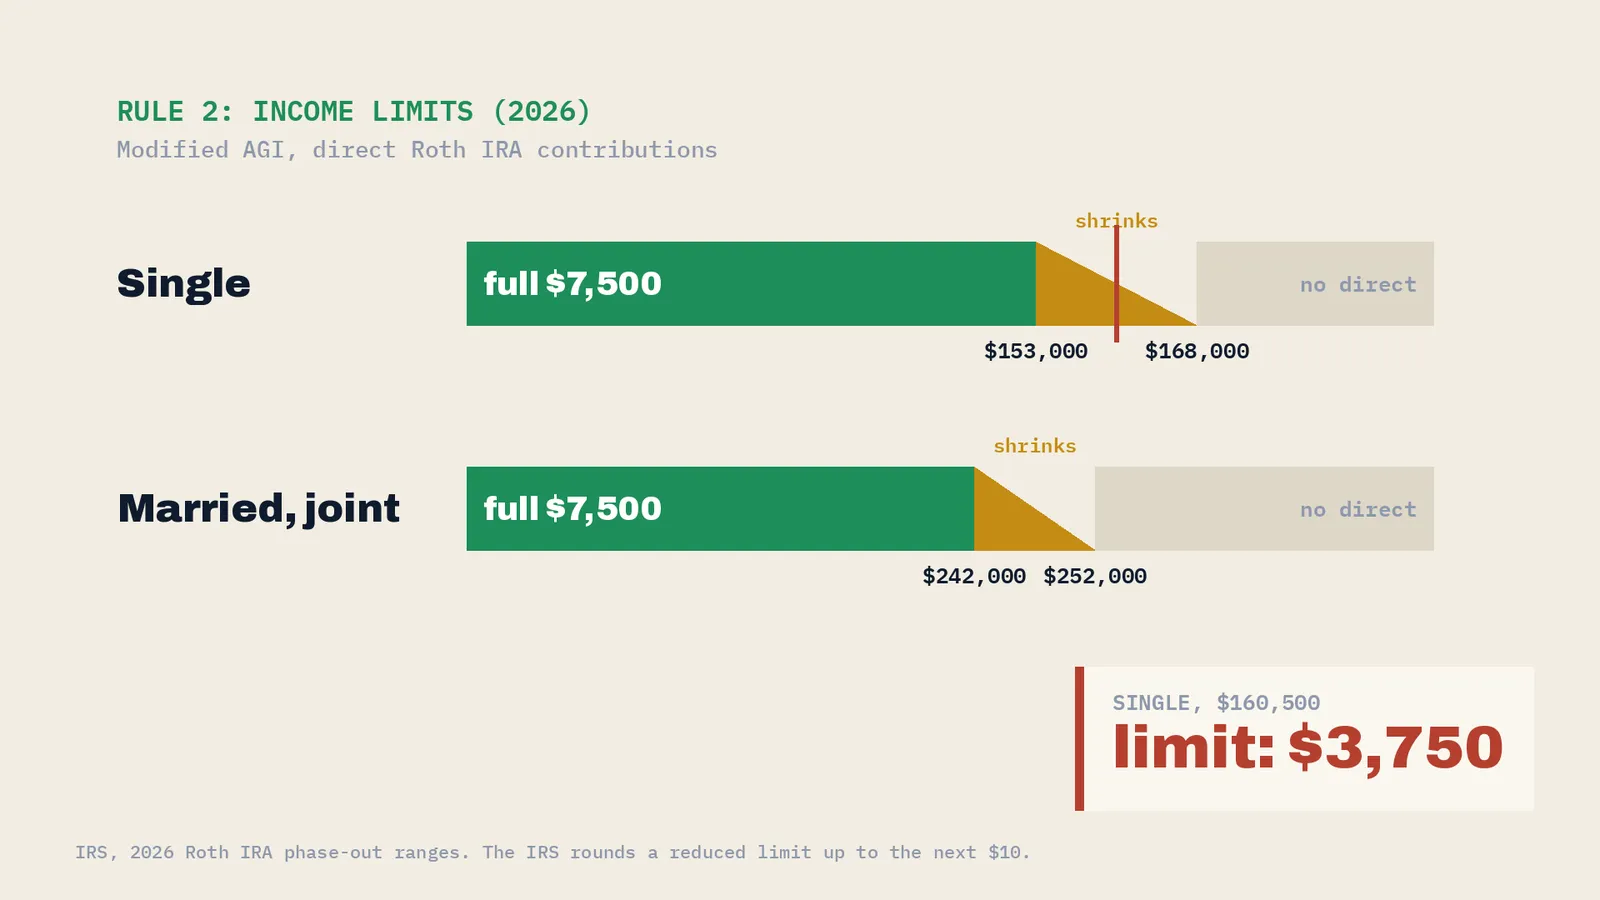
| Filing status | Full $7,500 | Shrinks | No direct contribution |
|---|---|---|---|
| Single | Under $153,000 | $153,000 to $168,000 | Over $168,000 |
| Married filing jointly | Under $242,000 | $242,000 to $252,000 | Over $252,000 |
These use modified AGI. Halfway through the single range, at $160,500, the limit is about half: $3,750.
Rule 3: the spousal IRA
A spouse with no paycheck can still have an IRA. File jointly, and the working spouse’s pay can cover both, up to $7,500 each.
What maxing it does
| $7,500 a year, 25 to 65 | Put in | At 65 |
|---|---|---|
| At 8% | $300,000 | $2,181,880, tax-free |
| Honest Check at 6% | $300,000 | $1,244,682 |
Even at 6%, that’s more than four times what she put in.
Rule 4: the backdoor Roth
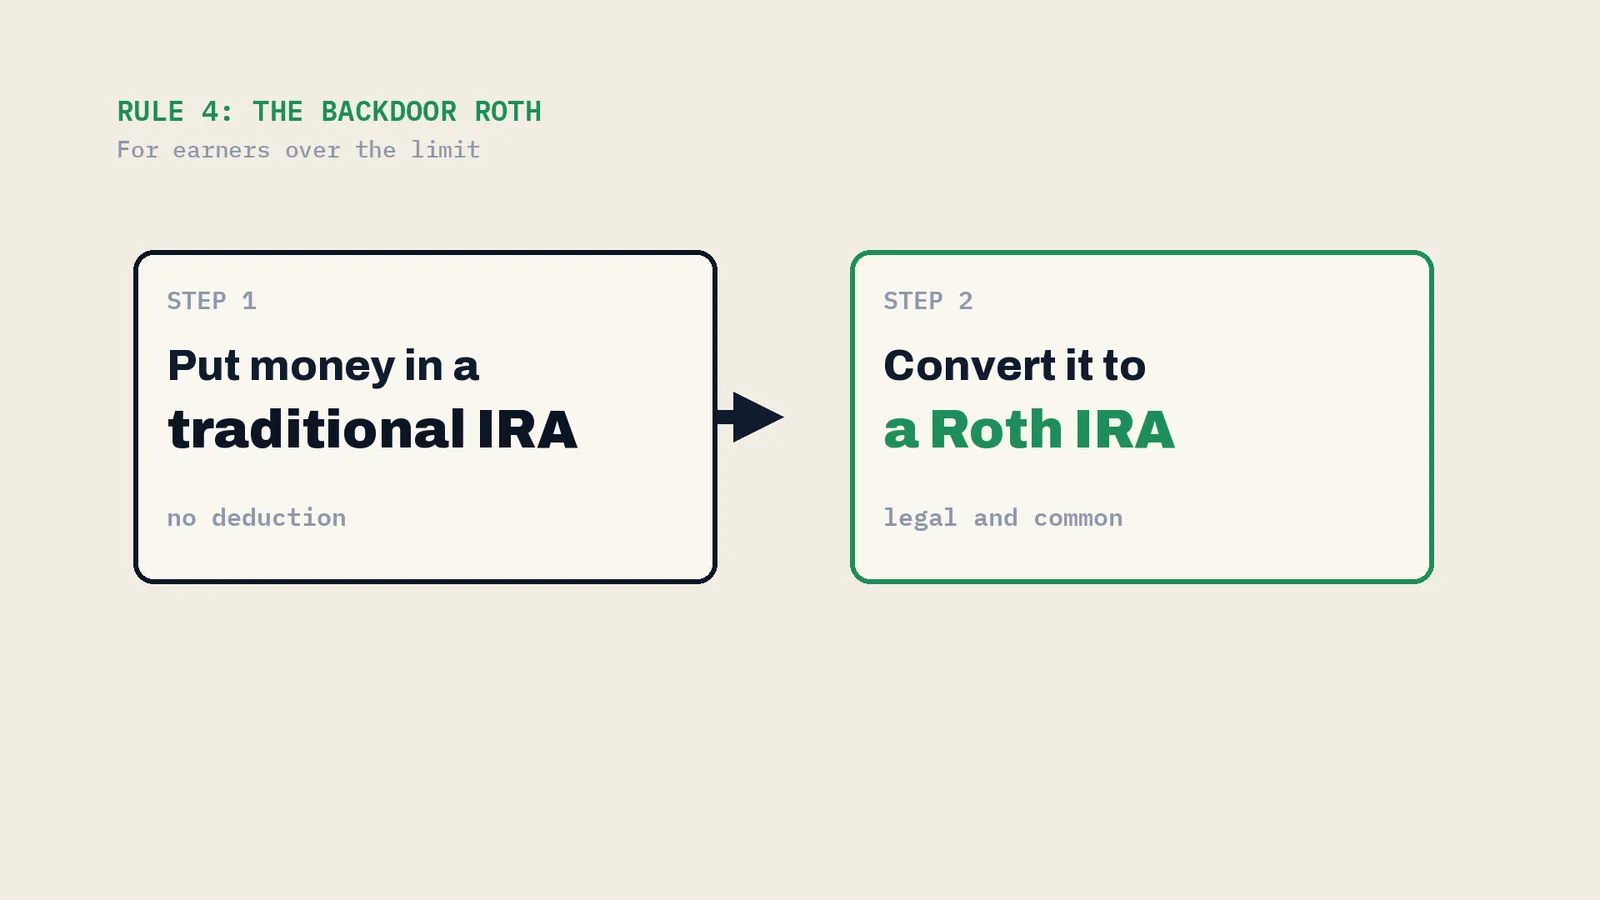
Earn too much? Put money in a traditional IRA without taking a deduction, then convert it to a Roth. It’s legal and common.
CPA Note from Daryl (tax year 2026). If you already have pre-tax money in any traditional, SEP or SIMPLE IRA, the pro-rata rule makes part of that conversion taxable. Form 8606 keeps track. General information, not tax advice for your situation.
CPA Note from Daryl. You can make last year’s contribution up until the tax-filing deadline, usually April 15. And at 50 and older, the limit goes up to $8,600.
Next up: what to actually buy inside the Roth. What’s an ETF? Meet our 7.
How the math works
Annual contributions are entered in the QWOS Roth IRA Calculator below, which spreads them monthly ($625 a month for $7,500; $250 for $3,000), 8% a year compounded monthly (6% for the Honest Check). The phase-out example is $7,500 × ($168,000 − $160,500) ÷ $15,000.
Education, not financial or tax advice. Projections assume steady returns; real returns vary and can be negative.
Sources: IRS: 2026 IRA limit, catch-up and Roth phase-out ranges · Vanguard: how to set up a backdoor IRA