



Maya is 25. She just decided to invest $500 a month. Marcus is 35, same job level, same $500 a month. He just started too, ten years later than Maya.
How much can ten years really cost? We ran it.
The experiment
Everything is the same except the starting line:
- Same amount: $500 a month
- Same investment: a plain S&P 500 index fund
- Same return: 8% a year
- Same finish: both stop at 65
The result
| Maya, starts at 25 | Marcus, starts at 35 | |
|---|---|---|
| Years investing | 40 | 30 |
| Total put in | $240,000 | $180,000 |
| Balance at 65 | $1,745,504 | $745,180 |
| Growth (money they never deposited) | $1,505,504 | $565,180 |
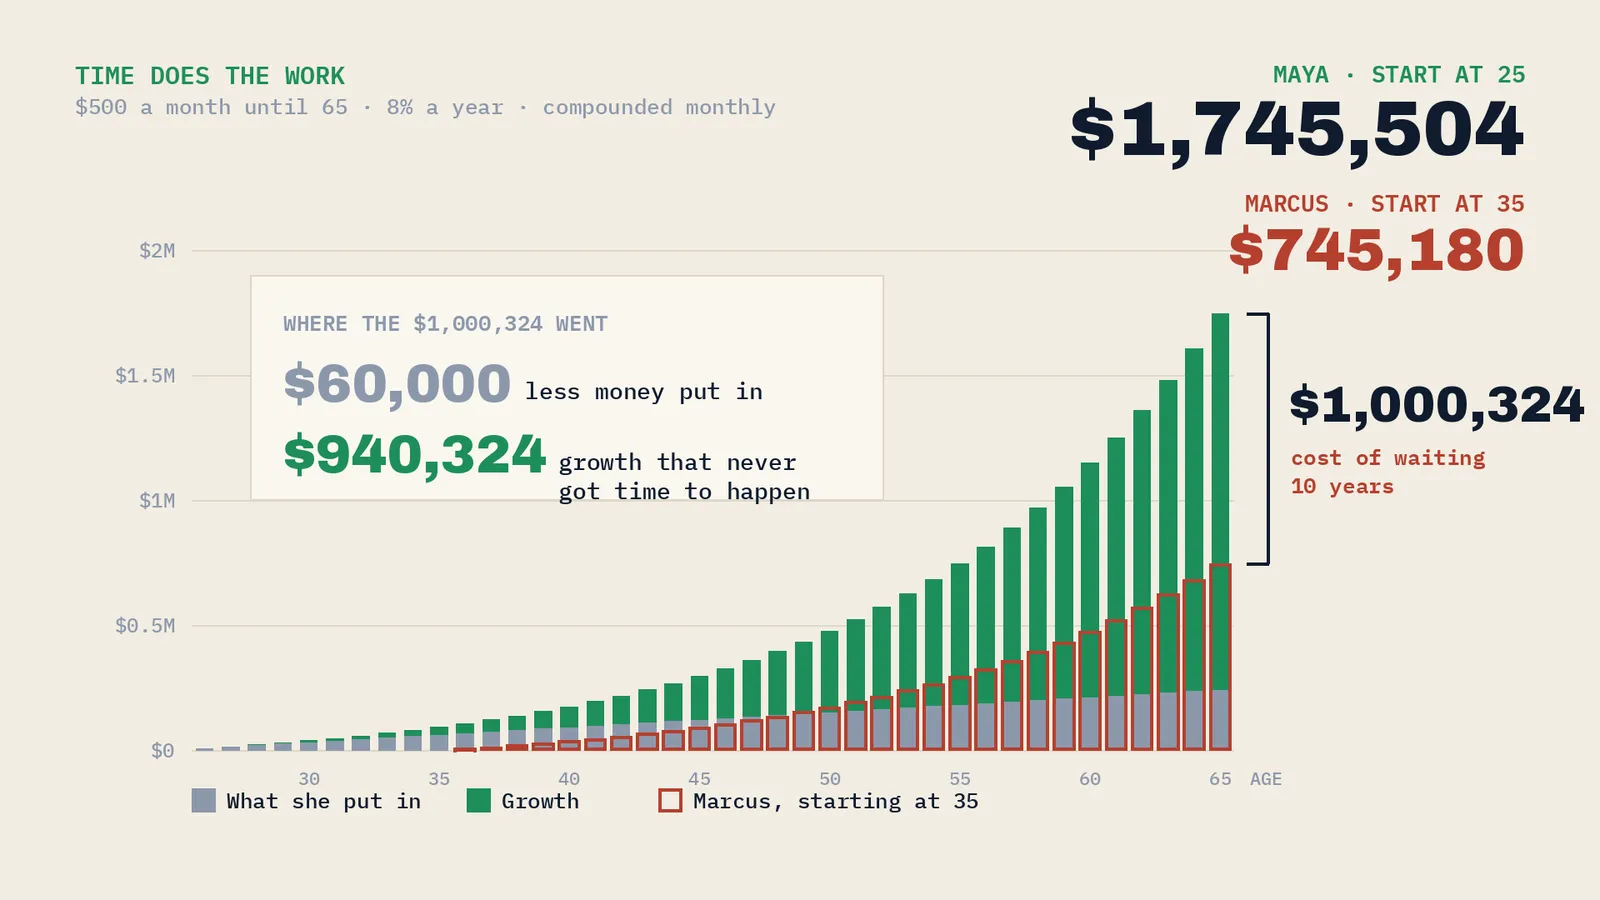
Waiting ten years cost Marcus $1,000,324. He only put in $60,000 less than Maya. The other $940,324 is growth he never gave time to happen.
Look at Maya’s tower: the gray part is what she put in. The green part is growth, and it’s 86% of the total.
Can Marcus catch up?
He can, but it’s expensive. To match Maya at 65, Marcus would need to invest $1,171 a month from age 35. That’s more than double. ($991 a month if returns are only 6%.)
That’s the price of buying back ten years.
The twist
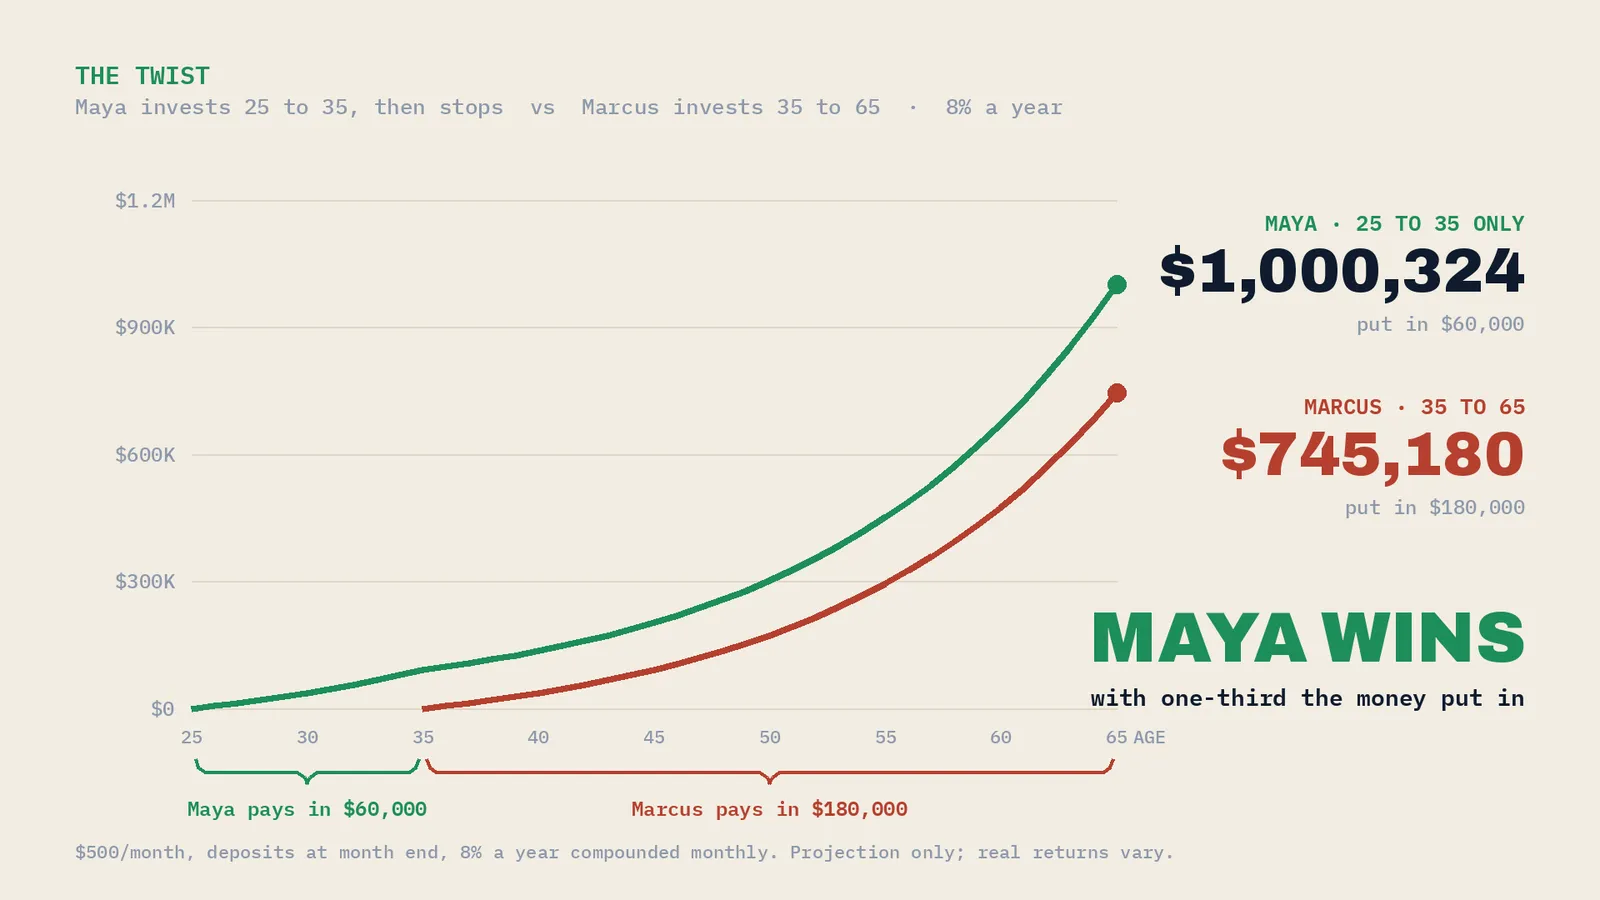
What if Maya invests only from 25 to 35, puts in $60,000, and then never adds another dollar?
At 8%, she still ends with $1,000,324 at 65. That’s more than Marcus, who invested for 30 years and put in three times as much.
The Honest Check: what if it’s only 6%?
We don’t promise 8%. So we run every example again at a more careful 6%.
| At 8% | At 6% | |
|---|---|---|
| Maya, 25 to 65 | $1,745,504 | $995,745 |
| Marcus, 35 to 65 | $745,180 | $502,258 |
| Cost of waiting 10 years | $1,000,324 | $493,488 |
| Maya, 25 to 35 only | $1,000,324 | $493,488 |
Starting early still nearly doubles the result at 6%. But the twist flips: at 6%, Marcus edges past stop-at-35 Maya, $502,258 to $493,488. He wins by $8,770.
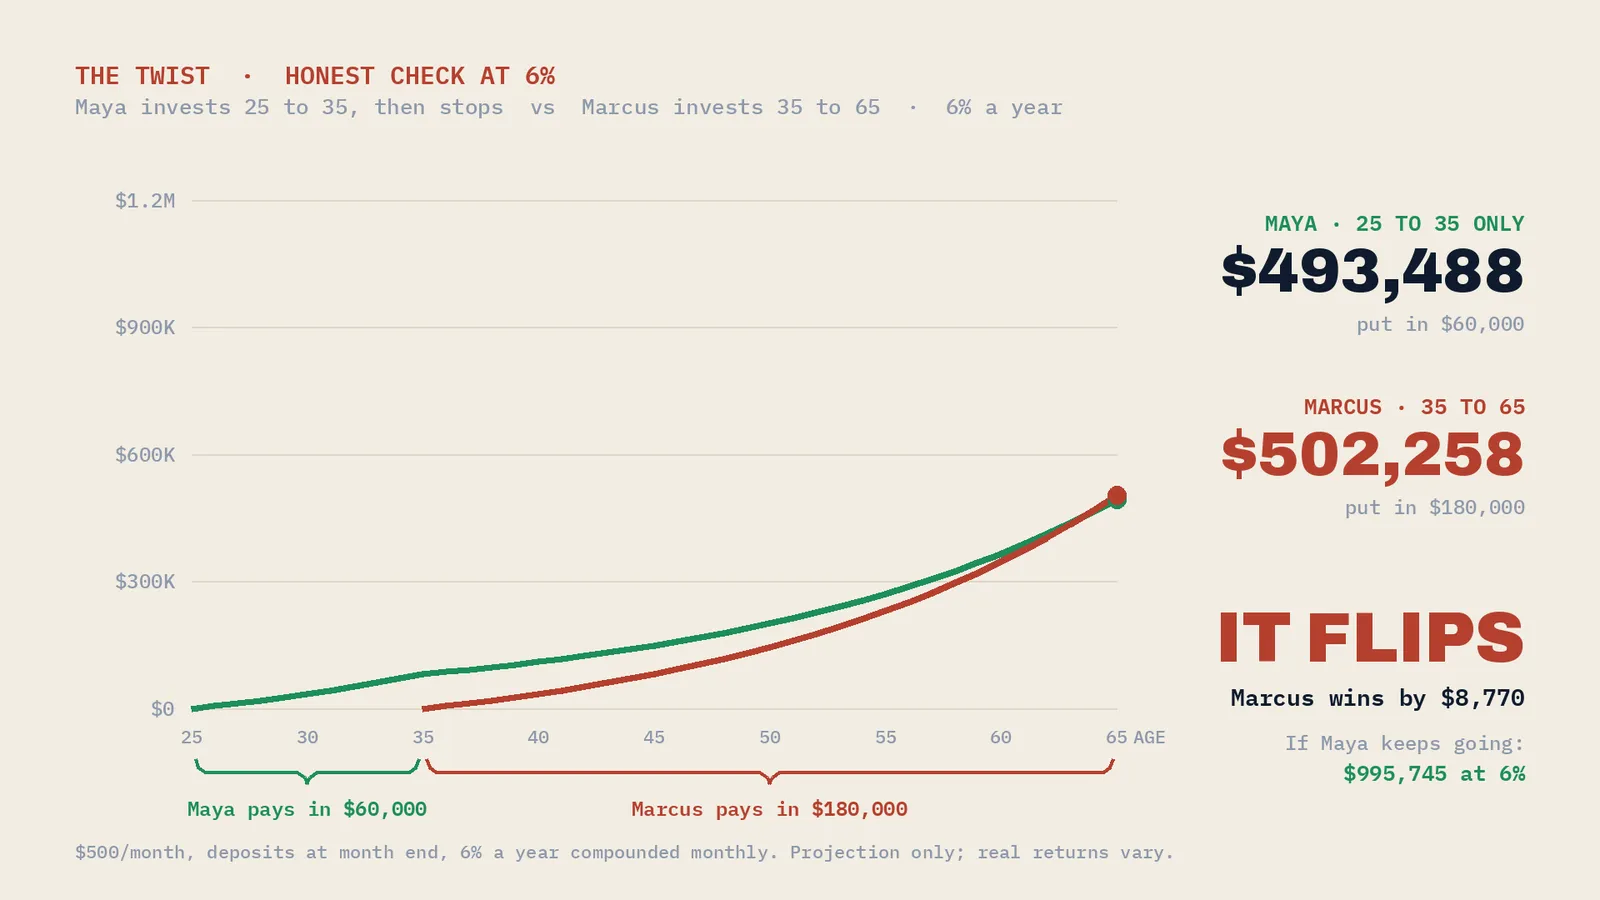
The real lesson isn’t “invest for ten years and quit.” It’s start early, and keep going.
Where does 8% come from?
SPY, the first S&P 500 ETF, has averaged about 10.9% a year since 1993, and that includes the dot-com crash and 2008. We run our numbers at 8% on purpose, below history, and check them again at 6%.
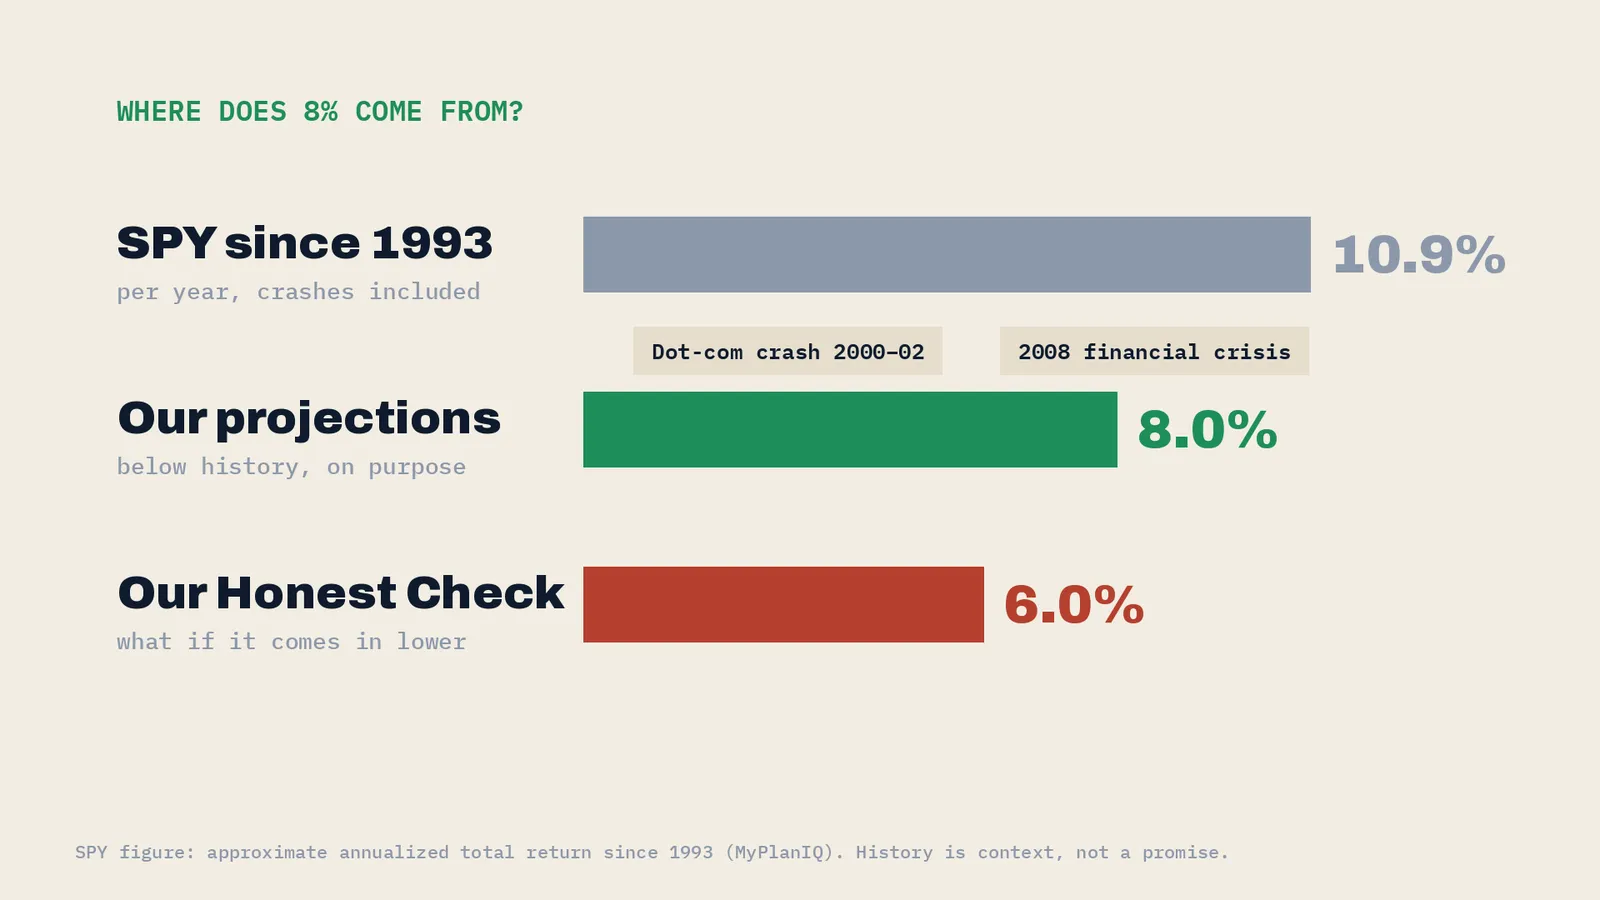
History is context, not a promise. Real returns move around year to year, and some years are negative.
Late is not never
If you’re 45 like Denise, $500 a month still grows to about $294,510 at 8% by 65 ($231,020 at 6%). The best time to start is the earliest one you still have.
How the math works
Every number assumes deposits at the end of each month, compounded monthly, with no taxes, fees or inflation adjustment. They match the QWOS Compound Interest Calculator exactly. The calculator below shows what waiting costs you, using your own numbers.
Education, not financial advice. Projections assume steady returns; real returns vary and can be negative.
Sources: SPY returns since 1993 (MyPlanIQ) · VOO becomes the first $1 trillion ETF (Nasdaq)