



Denise is 45. She’s a nurse, and she has nothing saved for retirement. In Episode 1, $500 a month from 45 got her $294,510 by 65. It looked like the sad ending. It isn’t.
What she does have
Twenty years, a steady $80,000 paycheck, and a hospital 401(k) with a match: 50 cents per dollar, up to 6% of pay.
The run: 15% of her pay
Denise puts in 15%. That’s $1,000 a month, and her hospital adds $200.
| Denise, 45 to 65 | Each month | At 65 (8%) |
|---|---|---|
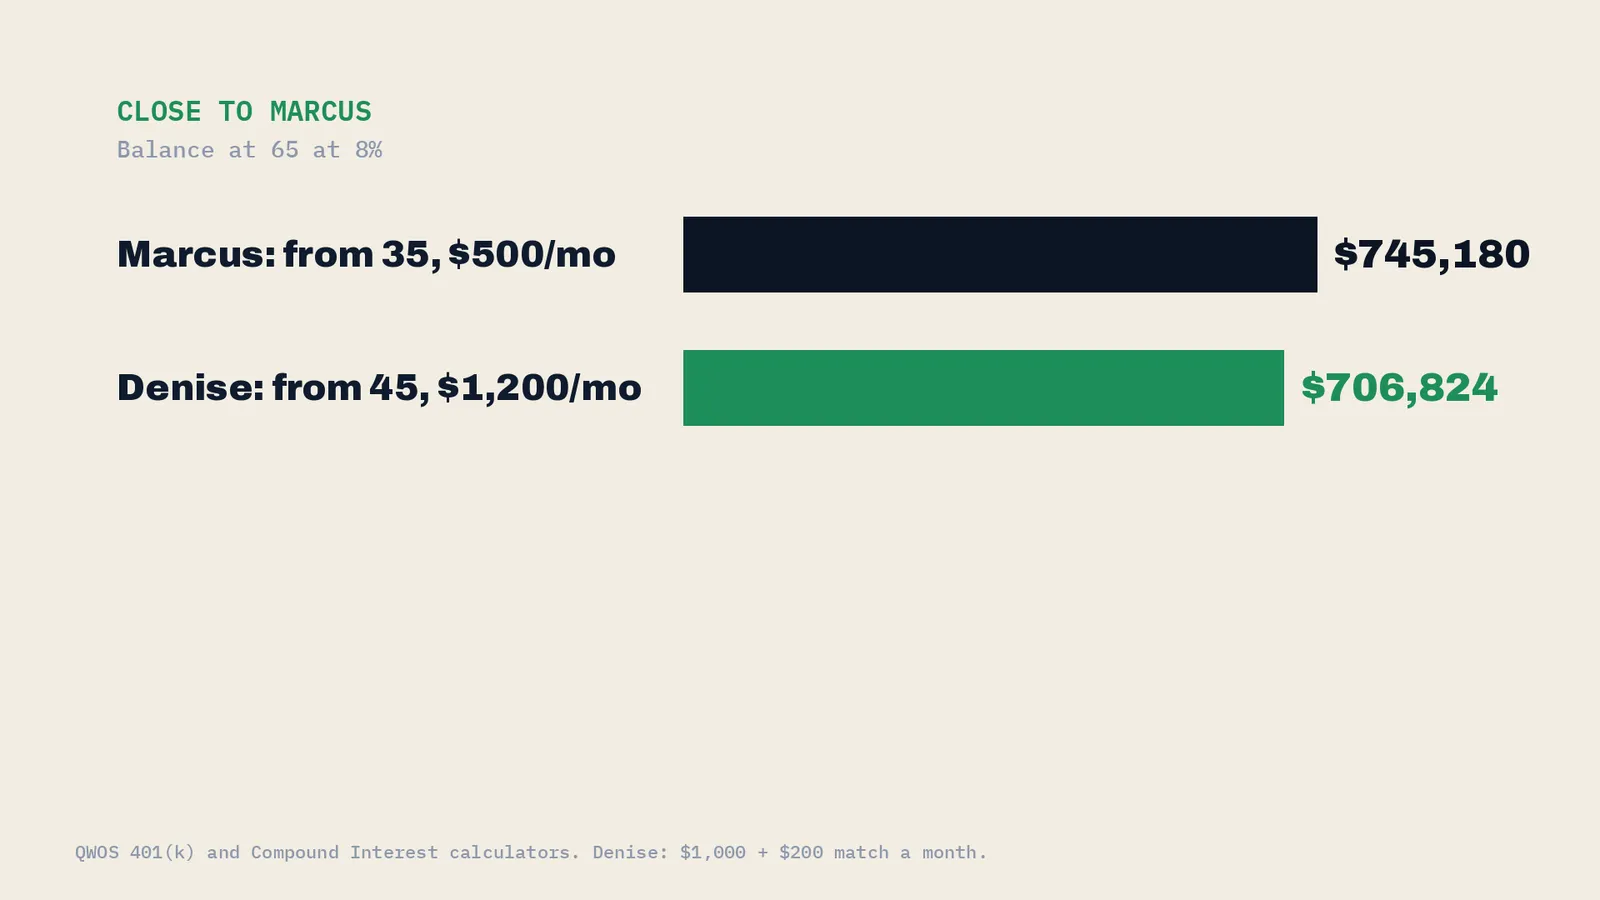
| 15% of $80,000 + match | $1,000 + $200 match | $706,824 |
That’s close to Marcus, who started 10 years earlier with $500 a month and gets $745,180. She pays more each month to make up for the lost decade, but she gets close.
The Honest Check: 6%
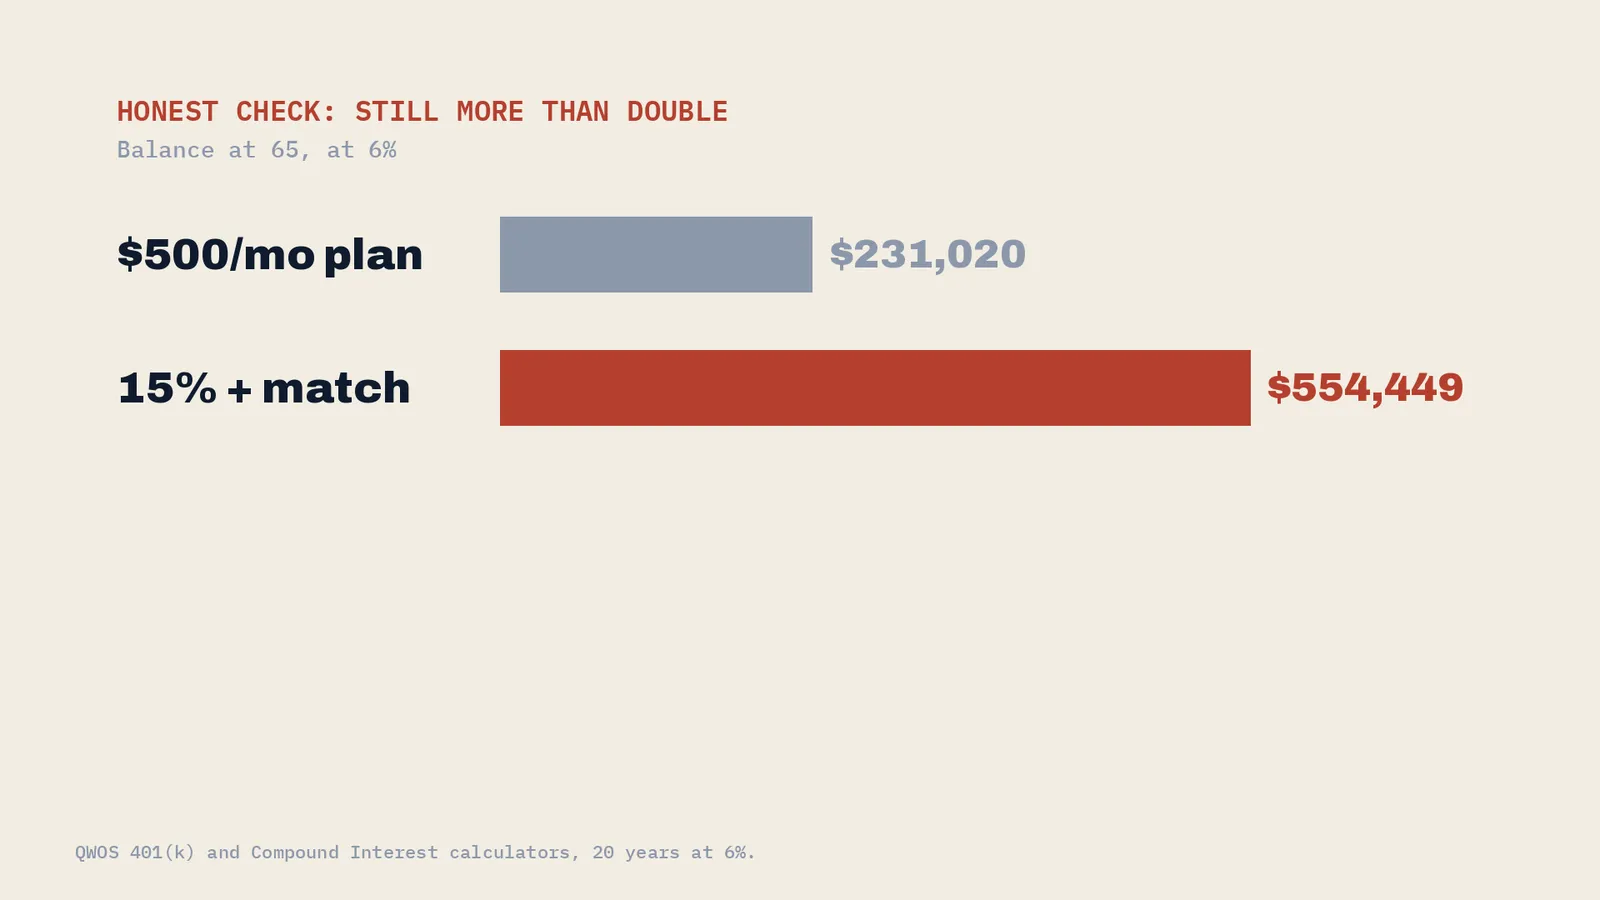
At 6% a year, her plan reaches $554,449. Less, but still more than twice what the $500-a-month plan gives at 6%: $231,020.
The part that stings: waiting
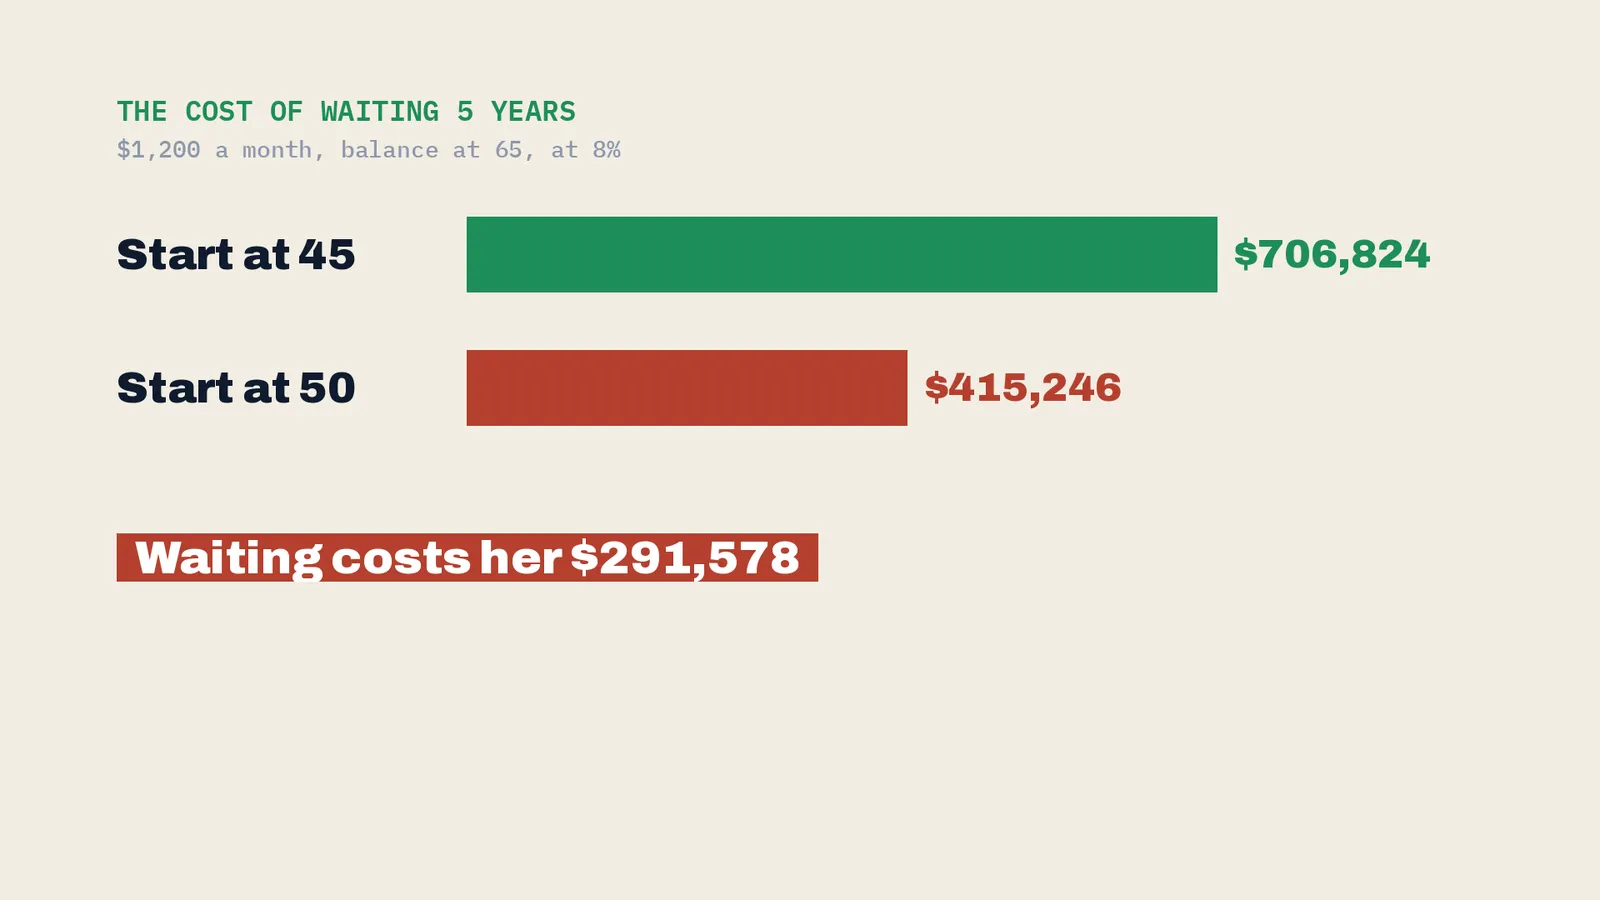
If Denise waits five more years and starts the same $1,200 a month at 50, she gets $415,246 by 65. Five years of waiting costs her $291,578.
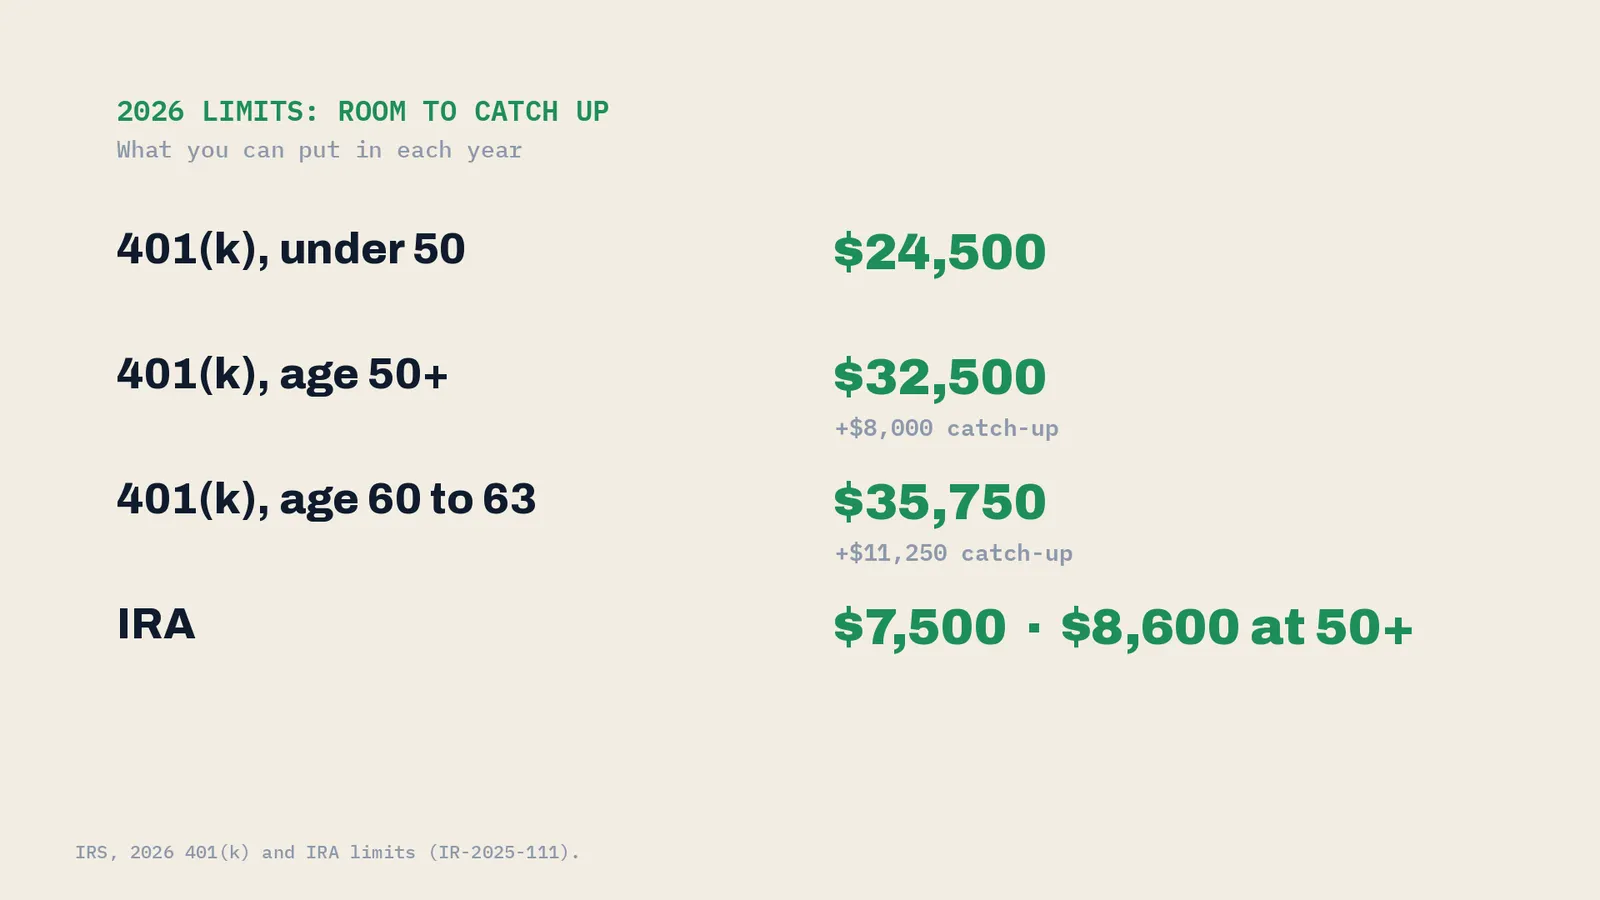
2026 limits: room to catch up
| Account | 2026 limit |
|---|---|
| 401(k), under 50 | $24,500 |
| 401(k), age 50+ | $32,500 (+$8,000 catch-up) |
| 401(k), age 60 to 63 | $35,750 (+$11,250 catch-up) |
| IRA | $7,500, or $8,600 at 50+ |
CPA Note from Daryl (tax year 2026). New this year: if you’re 50 or older and earned more than $150,000 in FICA wages last year, your catch-up contributions have to go in as Roth (after tax). General information, not tax advice for your situation.
Real talk
Fifteen percent is a lot. For Denise, it might mean keeping the car a few more years. And this doesn’t count Social Security, which she’ll have too. But the answer to “Is it too late?” is no. It’s just more expensive than it was at 35.
Next up: how much is enough? Your FIRE number and the 4% rule.
How the math works
Contributions are monthly ($1,000 from Denise, $200 match) and compound monthly, as in the QWOS 401(k) Calculator below: $80,000 salary, 15% contribution, 50% match up to 6% of pay, age 45, 20 years. The $500-a-month figures come from the QWOS Compound Interest Calculator. Waiting: same plan from age 50, 15 years.
Education, not financial advice. Hypothetical returns; real results vary and losses happen.
Sources: IRS: 2026 401(k) and IRA limits · CAPTRUST: final Roth catch-up regulations