



Marcus is 40. New job, better title. And one form he almost signed without reading: what to do with his old 401(k).
What he built
Five years of the plan from Episode 4: a $60,000 salary, 6% in, a 50% match up to 6%, 8% a year.
| His contributions | $18,000 |
| Employer match | $9,000 |
| Growth | $6,065 |
| Balance | $33,065 |
Four choices
- Leave it in the old plan.
- Roll it into the new 401(k).
- Roll it into an IRA, where he can pick funds like VOO.
- Cash it out.
The first three keep it growing. The fourth one is the trap.
What cashing out really costs
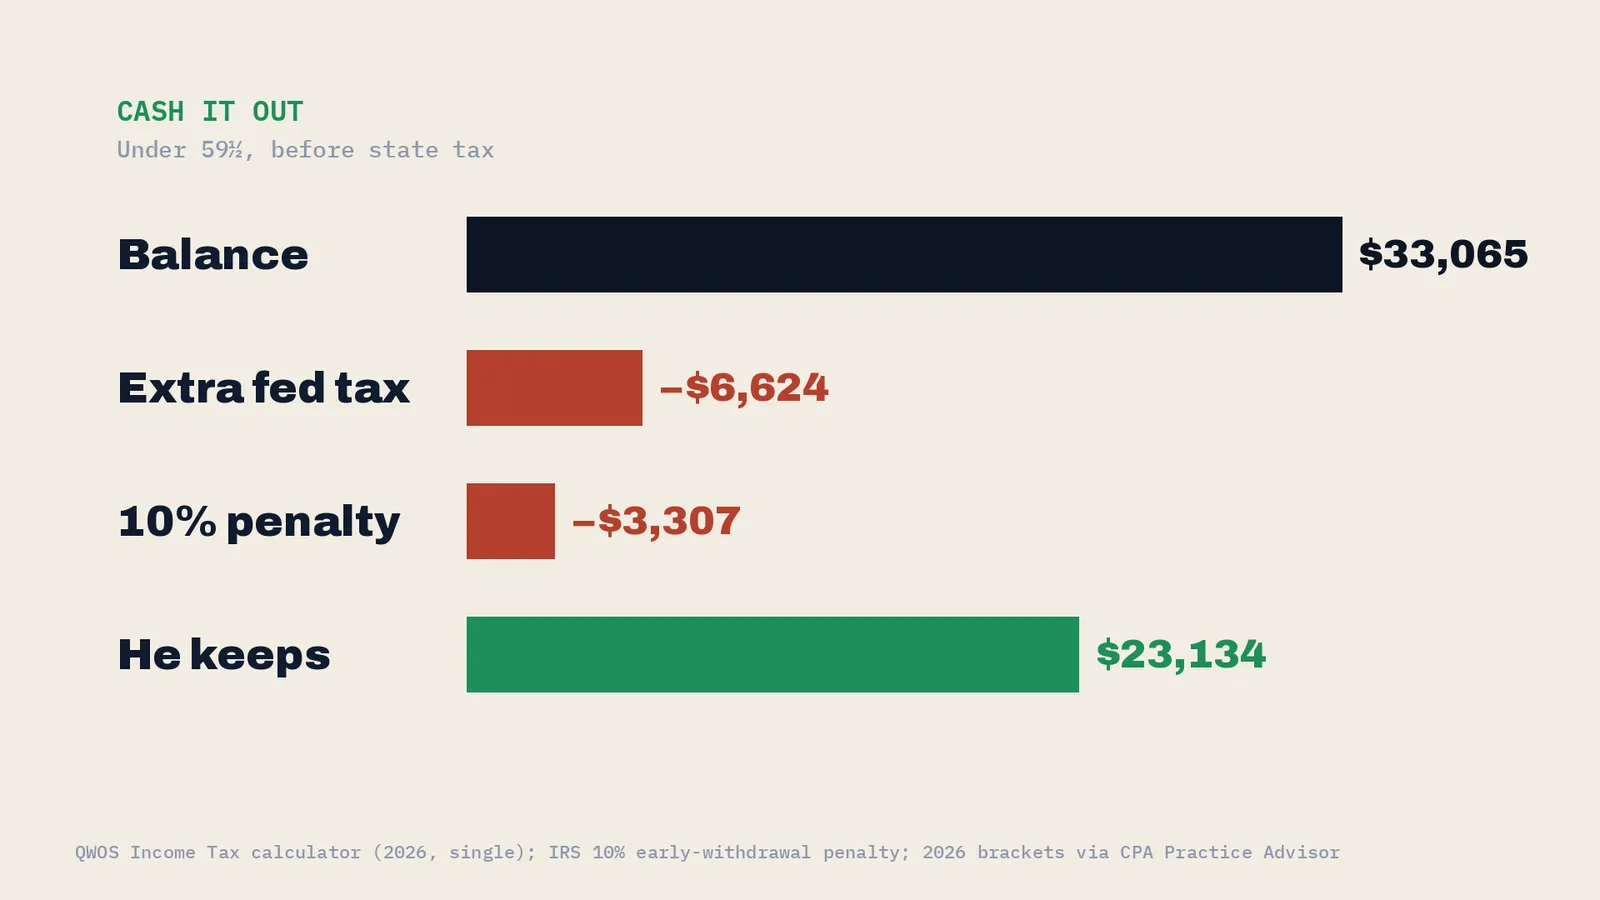
The $33,065 counts as income this year. On top of his $60,000 salary, that pushes part of it into the 22% bracket.
| Federal tax on $60,000 | $5,020 |
| Federal tax on $93,065 | $11,644 |
| Extra federal tax | $6,624 |
| 10% penalty (under 59½) | $3,307 |
| He keeps | $23,134 |
Almost a third gone, before state tax.
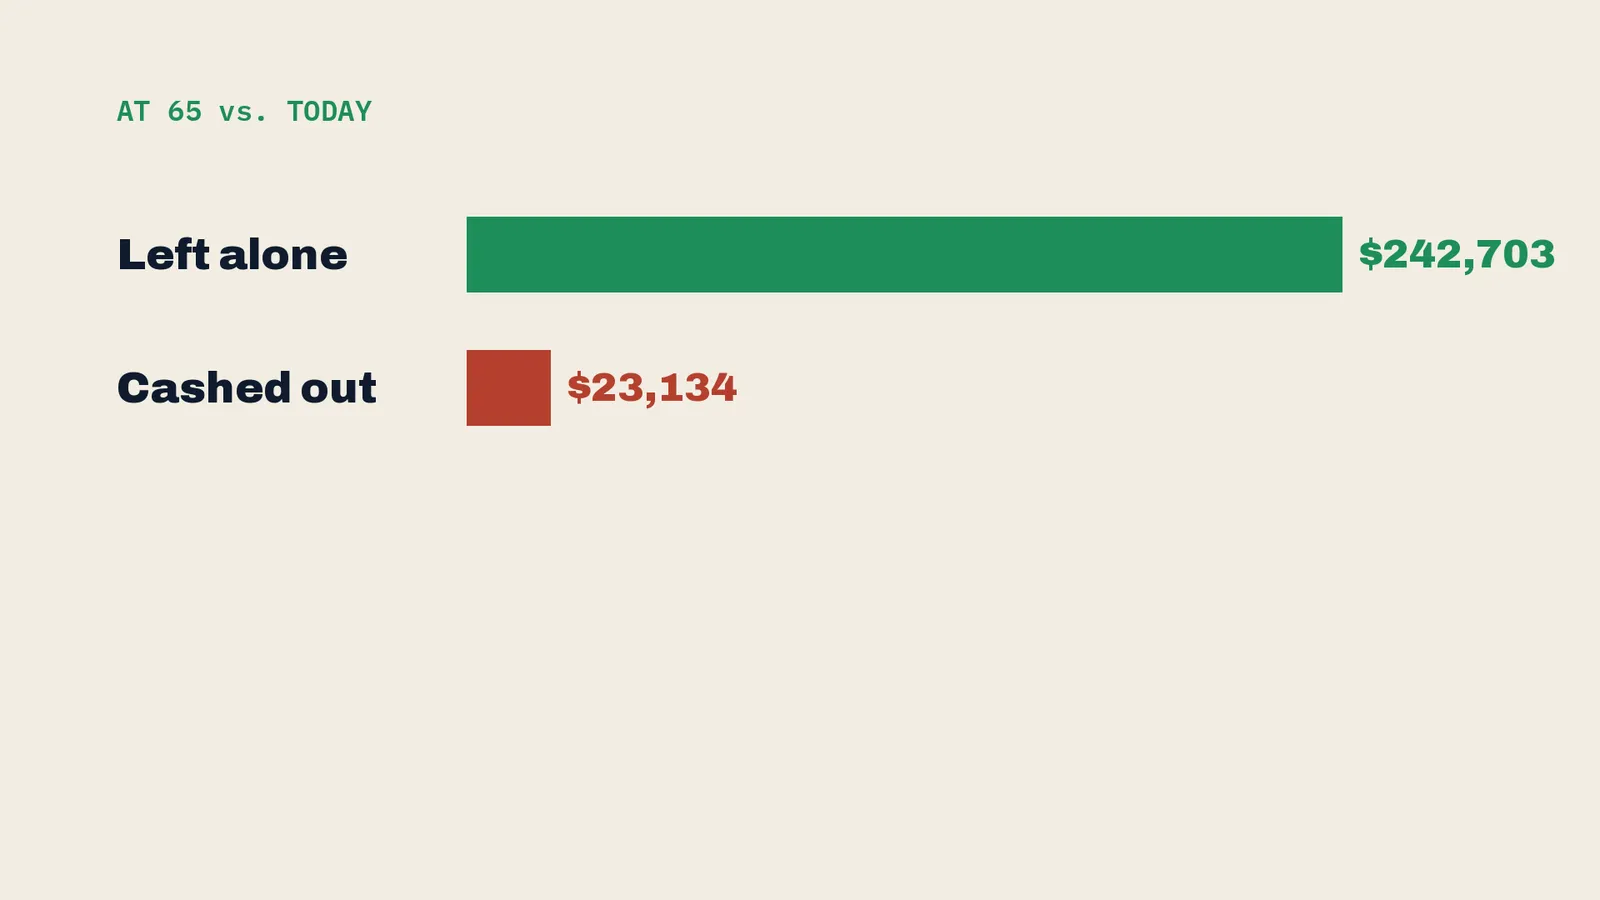
And that’s the small part. Left alone at 8%, never adding another dollar, $33,065 becomes $242,703 by 65.
The Honest Check: 6%
At 6%, the same $33,065 grows to $147,634 by 65. Still more than six times the $23,134 he’d keep by cashing out.
Which rollover?
Old plan, new plan, or IRA: all three keep the money growing tax-deferred. Check the fees and the fund choices, and pick the one you’ll actually keep an eye on.
CPA note from Daryl (tax year 2026)
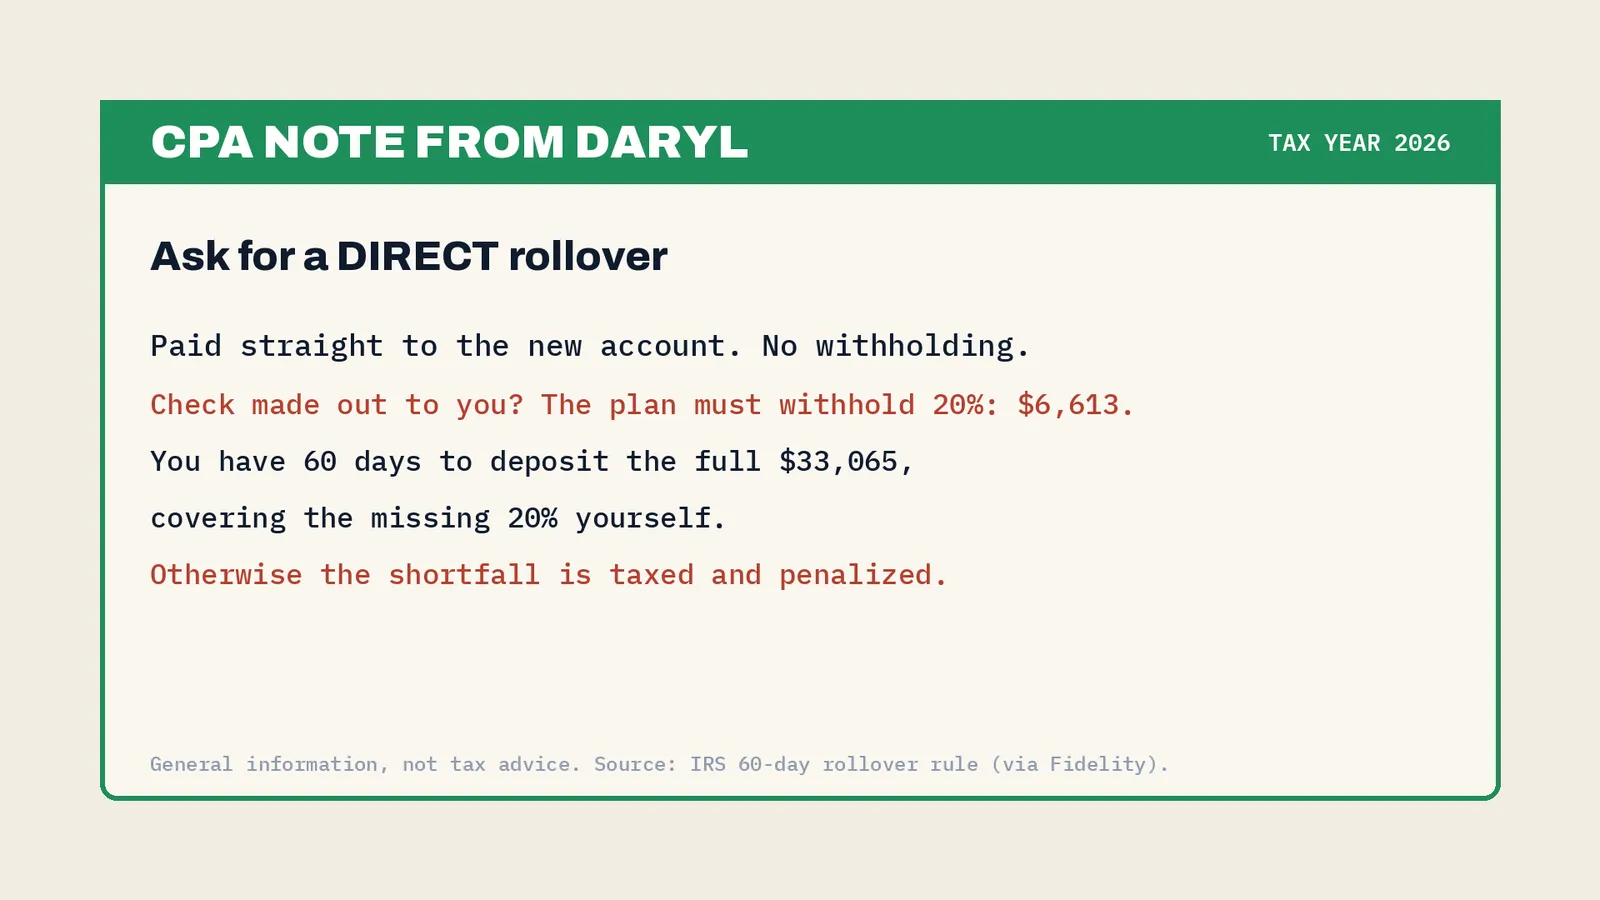
Ask for a direct rollover, paid straight to the new account. If the check is made out to you, the plan must withhold 20% ($6,613 here), and you have 60 days to deposit the full $33,065, covering the missing 20% yourself. Any shortfall is taxed and penalized.
Changing jobs is a raise. Don’t let your old 401(k) be the price.
Next up: the new job came with a $15,000 raise. A year later, Marcus is saving less than before.
How the math works
Balance: QWOS 401(k) Calculator ($60,000 salary, 6% contribution, 50% match up to 6%, 8% return, age 35, 5 years). Taxes: QWOS Income Tax Calculator, single filer, 2026 standard deduction ($5,020 on $60,000; $11,644 on $93,065). Growth to 65: QWOS Compound Interest Calculator ($33,065, no additions, 25 years, monthly compounding). The 10% penalty and 20% withholding are 10% and 20% of $33,065. Sources: IRS 60-day rollover rule (via Fidelity); 2026 brackets (CPA Practice Advisor).
Education, not financial or tax advice. Hypothetical returns; real results vary and losses happen.