



Maya’s 31. She’s invested $1,400 a month since she was 25. Today she found out she could stop saving for retirement. Completely. And still retire on time.
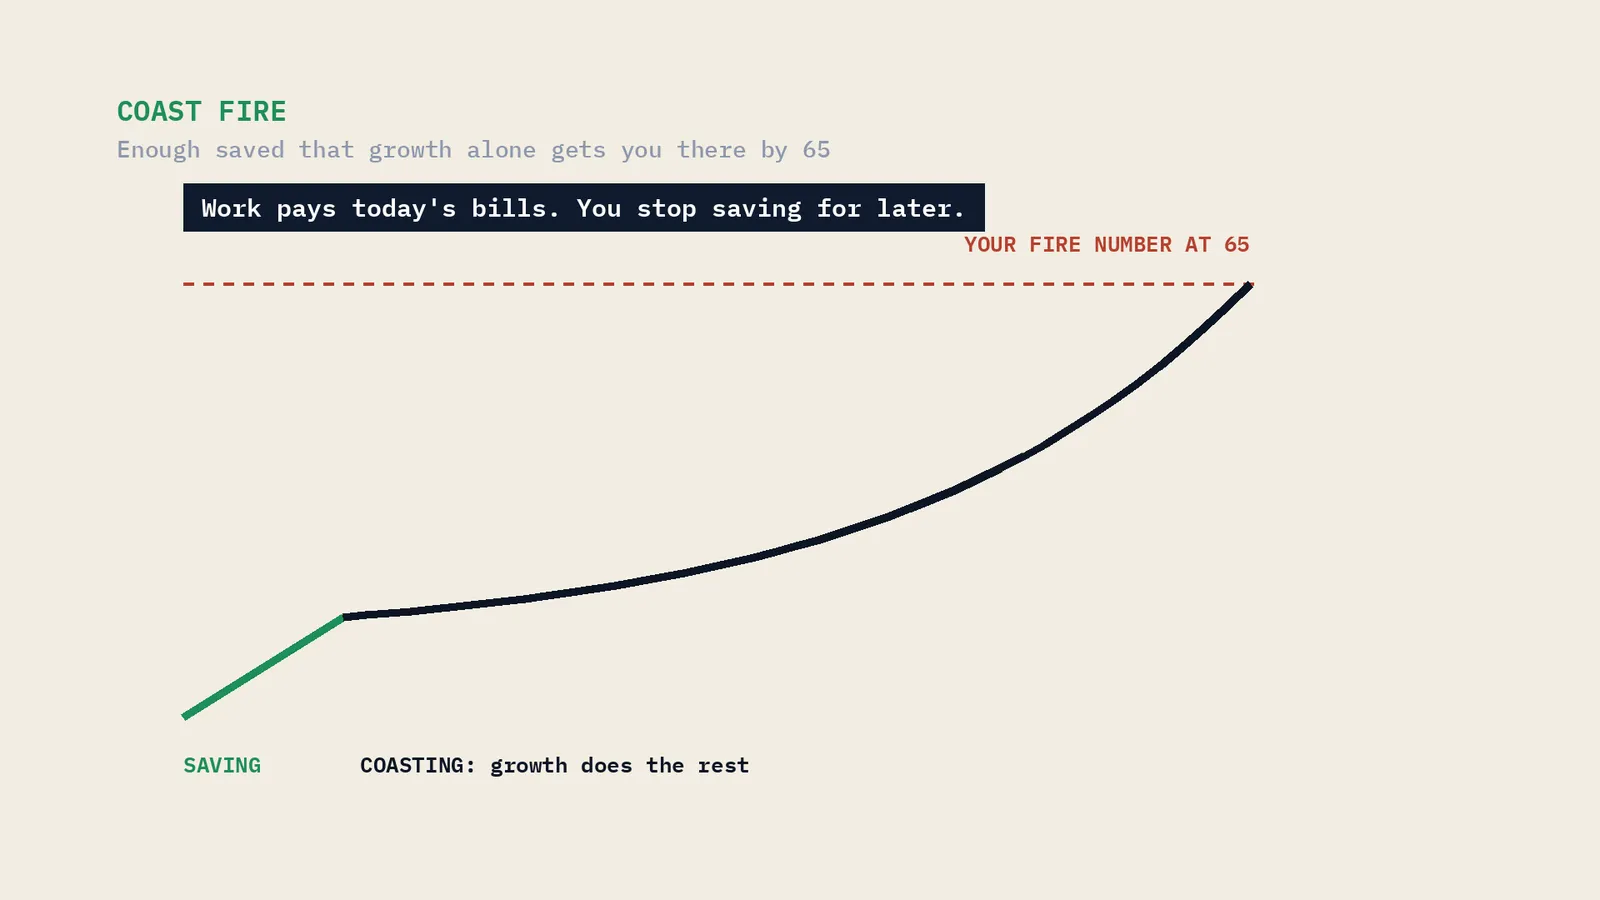
What Coast FIRE means
You’ve saved enough that growth alone gets you to your full number by 65. You still work to pay today’s bills. You just stop saving for later.
Maya’s numbers
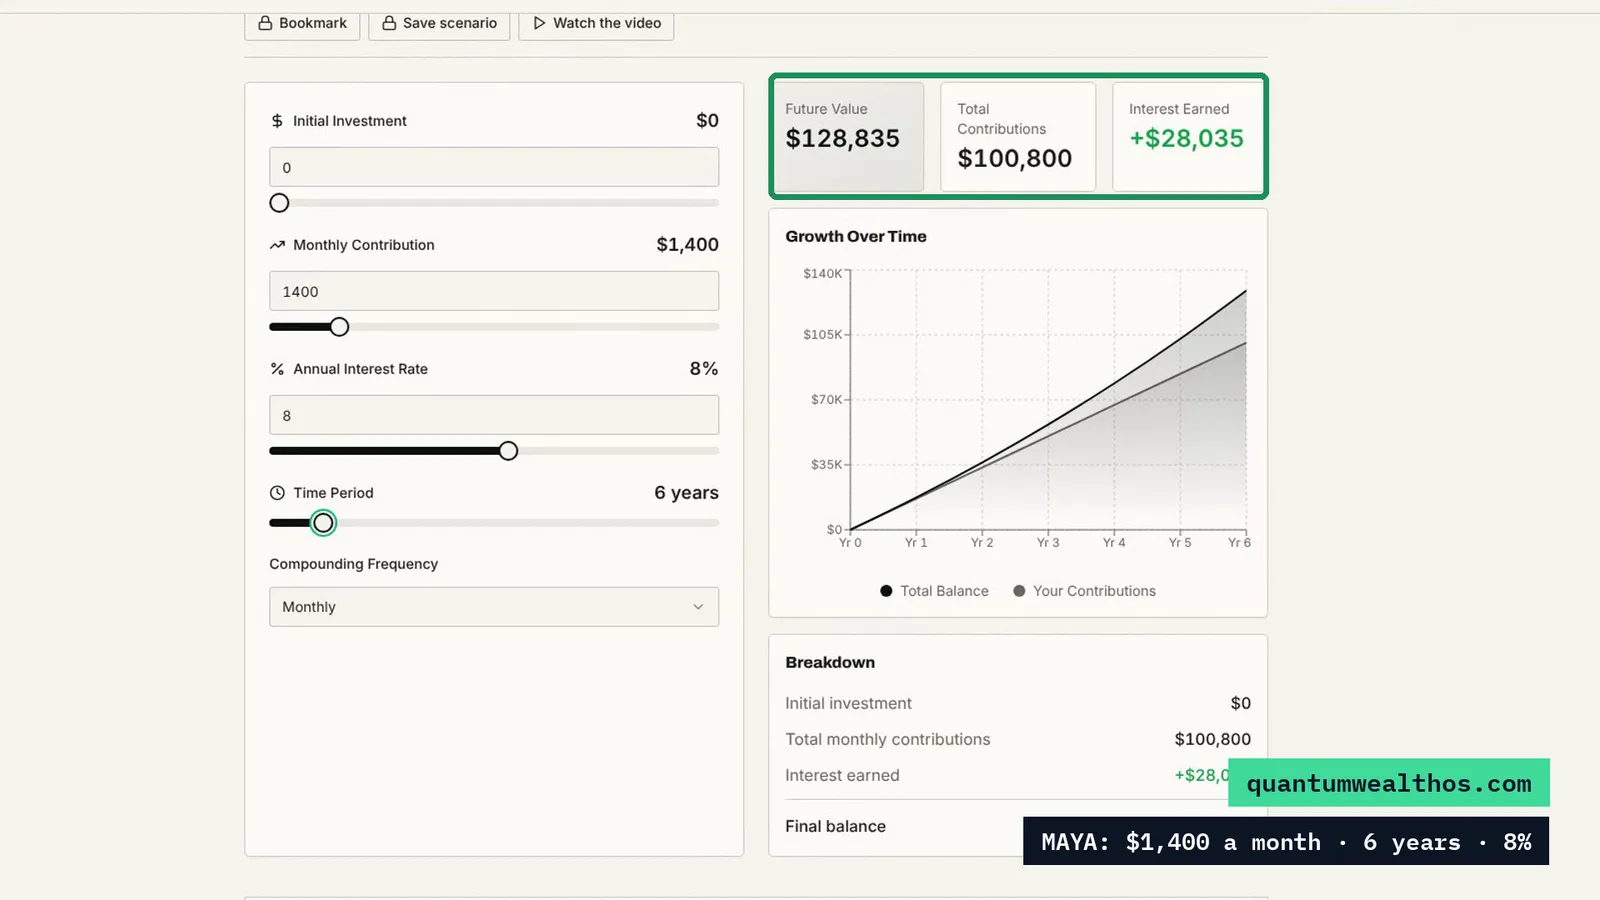
Six years of $1,400 a month at 8%: $128,835. She put in $100,800.
She spends $2,100 a month, $25,200 a year. With 3% inflation for 34 years, that’s a FIRE number at 65 of $1,721,100.
| At 8% | |
|---|---|
| Coast FIRE number (needed today) | $125,718 |
| What she has | $128,835 |
| Left alone, at 65 | $1,763,768 |
She has options now: a lower-stress job that covers her $2,100, part-time work, a year to try something. Or she keeps investing and retires way before 65.
The Honest Check: 6%
| At 6% | |
|---|---|
| Coast FIRE number | $237,360 |
| How far she is | 54.3% |
| $128,835 left alone, at 65 | $934,186 (not enough) |
At 6%, she’d keep investing until 37. Then $294,210 beats her coast number of $281,980.
The catches
- Coast FIRE assumes you never touch the money.
- And that your spending only grows with inflation.
- If your job has a 401(k) match, keep getting it. That’s free money, not saving.
The earlier you start, the sooner you can coast. Find your number, then check it at 6%.
Next up: Marcus changed jobs, and almost made a $242,703 mistake with his old 401(k).
How the math works
Maya’s balance comes from the QWOS Compound Interest Calculator ($1,400 a month, 6 years at 8%; 12 years at 6% for $294,210). Coast numbers come from the QWOS Coast FIRE Calculator below: current age 31 (37 for the last row), retire at 65, $25,200 a year in today’s dollars, 4% withdrawal rate, 3% inflation.
Education, not financial advice. Hypothetical returns; real results vary and losses happen.