



Marcus got the promotion. He’s 40, and his salary just jumped to $200,000. Great news, with one catch: he earned his way out of the Roth IRA.
The 2026 rule
| Roth IRA, 2026 | |
|---|---|
| Contribution limit | $7,500 ($8,600 at 50+) |
| Single: phases out | $153,000 to $168,000 |
| Married filing jointly | $242,000 to $252,000 |
The ranges use modified adjusted gross income. Marcus files single. His 12% to the 401(k), $24,000, comes off his taxable income, but he’s still at about $176,000. Over the line.
Why he cares
| Roth IRA calculator, $7,500 a year, 40 to 64 (limit held flat) | |
|---|---|
| Tax-free balance at 64 (8%) | $541,653 |
| Put in | $180,000 |
| Estimated tax savings vs. a taxable account (24% rate) | $86,797 |
The back door
The income limit applies to contributing to a Roth. There’s no income limit on converting money into one (there hasn’t been since 2010).
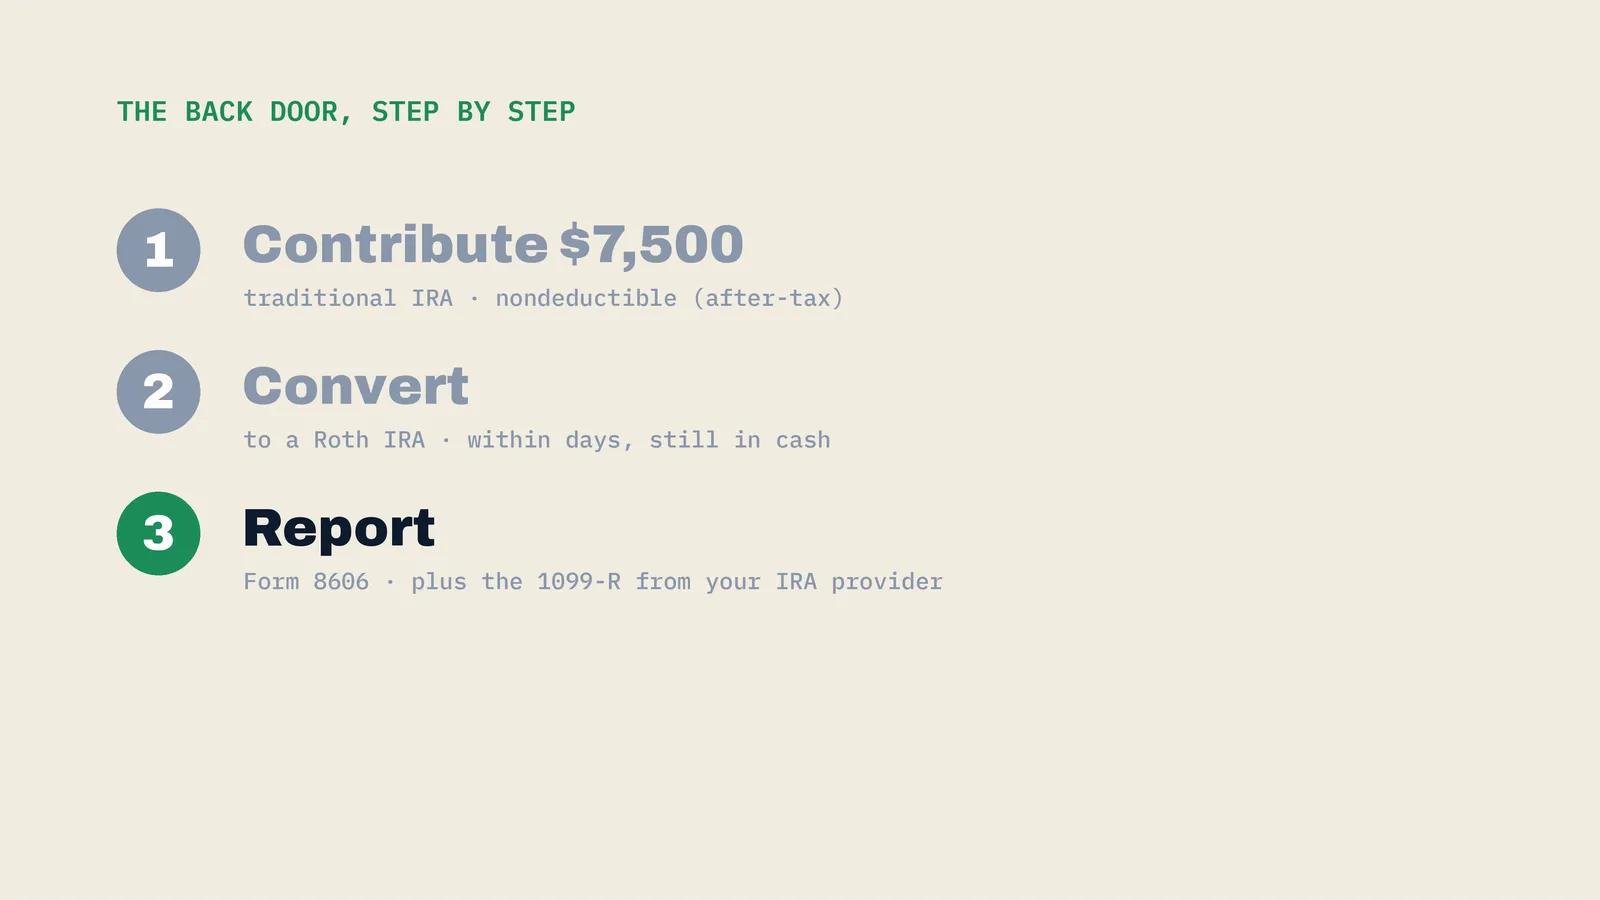
- Contribute $7,500 to a traditional IRA. Marcus has a 401(k) at work and earns well over $91,000, so he can’t deduct it. It goes in as after-tax money: a nondeductible contribution.
- Convert it to a Roth IRA. Many people do this within days, while the money is still in cash, so there’s little or no growth to tax.
- Report it. Form 8606 shows the IRS the money was already taxed and reports the conversion. Your IRA provider also sends a 1099-R.
The pro-rata trap
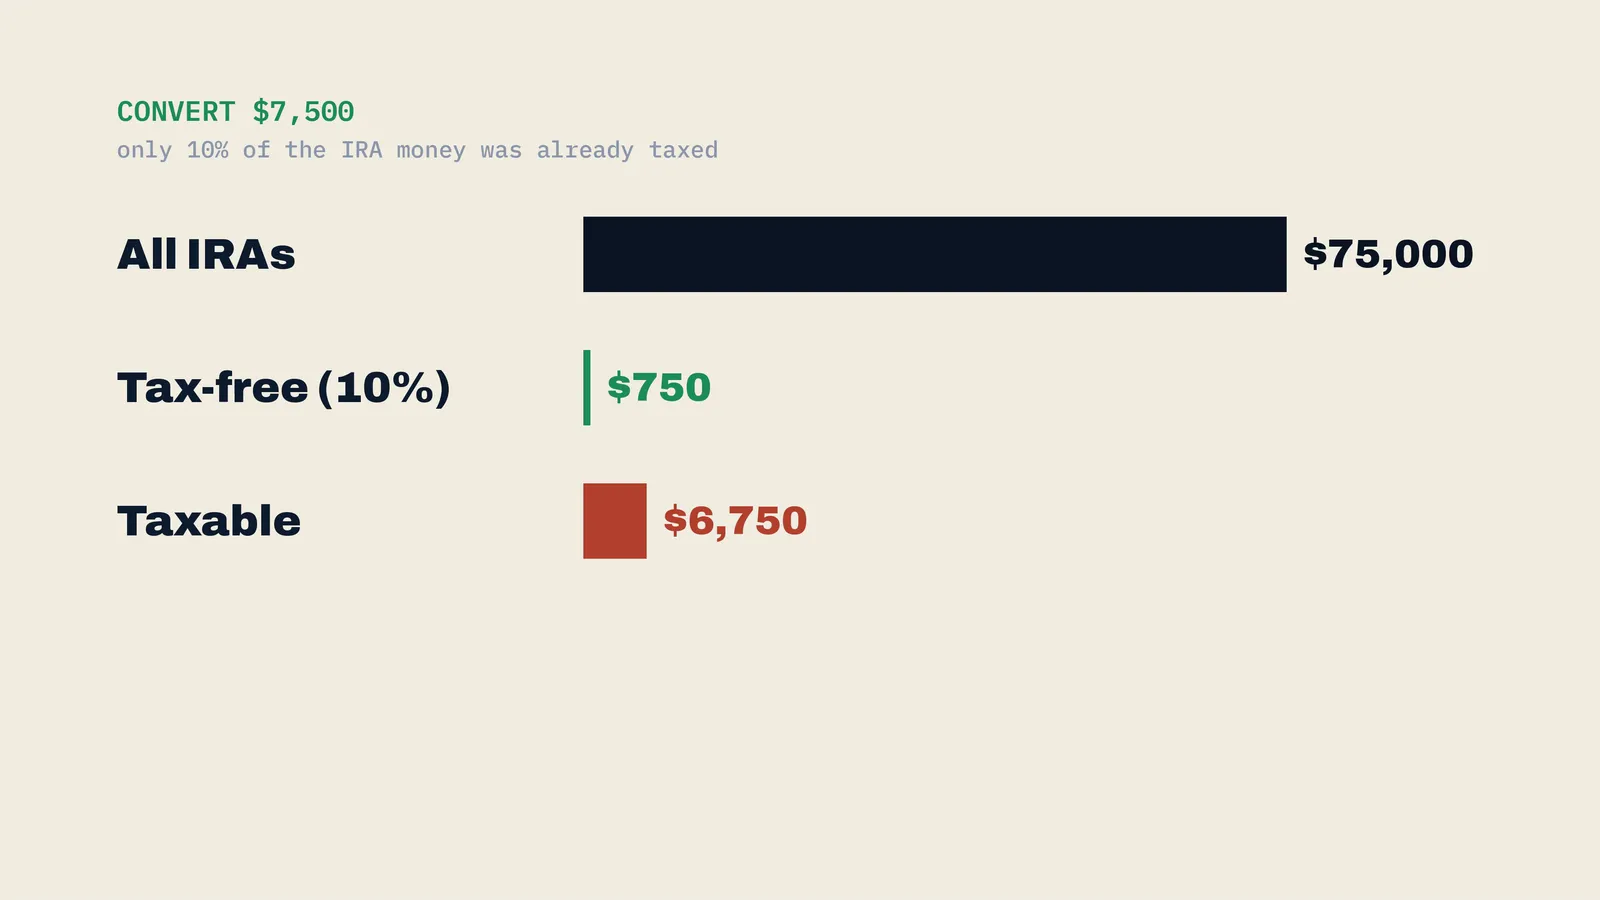
The IRS looks at all your traditional, SEP and SIMPLE IRAs together, as of December 31. Say you already have $67,500 of pre-tax money in an old rollover IRA (a hypothetical; Marcus has no other IRA money).
| Converting $7,500 | |
|---|---|
| All IRA money | $75,000 |
| Already taxed (10%) | $750 comes over tax-free |
| Taxable | $6,750 |
On the income tax calculator (single), $176,000 of income means $30,974 of federal tax. Add $6,750 and it’s $32,594: $1,620 of surprise tax on a move that was supposed to cost nothing.
The fix: many 401(k) plans accept roll-ins. Move the pre-tax IRA money into your 401(k) before December 31 and it no longer counts.
It’s an every-year move. For 2026, Marcus has until April 15, 2027, to make the contribution.
The Honest Check: 6%
| At 6% | |
|---|---|
| Roth at 64, tax-free | $400,697 |
| Estimated tax savings | $52,967 |
The pro-rata tax in the example is $1,620 at any return. Check before you convert.
CPA Note from Daryl (tax year 2026)
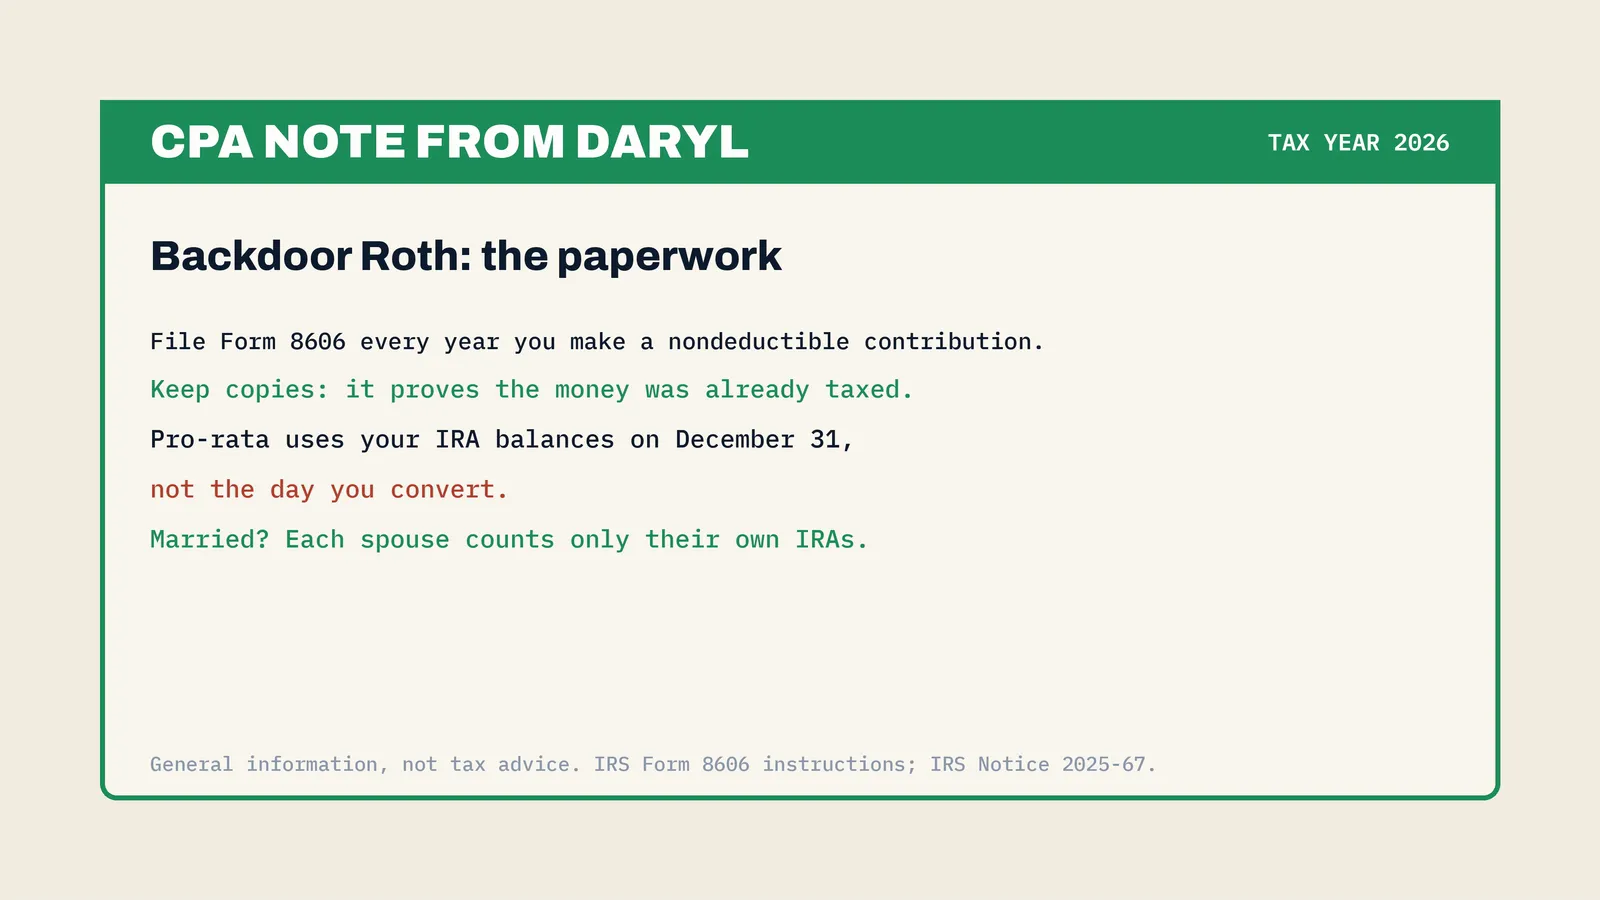
- File Form 8606 for every year you make a nondeductible contribution, and keep copies. It’s your proof the money was already taxed.
- The pro-rata math uses your IRA balances on December 31 of the year you convert, not the day you convert.
- Married? Each spouse’s IRAs are counted on their own, so each of you can do your own back door.
Next up: are you behind? What families in their mid-forties really have.
How the math works
Roth IRA: QWOS Roth IRA Calculator ($0 balance, $7,500 a year, age 40, 24 years, 24% tax rate, 8% or 6%). Tax: QWOS Income Tax Calculator (single, standard deduction $16,100; $176,000 and $182,750). Limits and phase-outs: IRS Notice 2025-67. Reporting: IRS Form 8606 instructions.
Education, not financial or tax advice. Hypothetical returns; real results vary and losses happen.